Fifteen-plus years of BC mortgage experience, distilled into practical writing on buying, renewing, refinancing, and building wealth through real estate.
When Every Economist Agrees on Rates, the Forecast Gets Riskier
A mortgage renewal letter doesn't wait for the forecasts to settle. It arrives with a date, a balance and a decision, while the headlines around it say rates should ease, probably, by next year. That reassurance is pleasant to read, but a forecast that rates will fall doesn't tell you what payment your household can safely carry if they don't. Learning to use forecasts without leaning your budget on them is one of the most useful skills a borrower can have.
If you've compared mortgage options while several forecasts promised lower rates, you know the feeling: you're signing something firm on the strength of something soft. Homeowners renewing across British Columbia feel it. So do first-time buyers deciding whether to wait for relief, and rental-property owners trying to keep a thin monthly margin from turning negative.
Why agreement does not make a rate forecast safer
When five bank economists publish similar outlooks, it can look like five separate confirmations. Usually it is closer to one view expressed five ways. Forecasters draw on the same inflation, employment and growth releases, and they often share the same assumptions about how the economy will respond. There is also a quiet professional incentive at work: being wrong alongside everyone else costs a forecaster far less than being wrong alone. So outlooks tend to cluster, and when the shared assumption breaks, they tend to miss together.
The data itself has limits. Published figures describe a period that has already passed, and they can be revised after the fact. Good forecasters also use forward-looking information, such as market pricing and surveys. Still, shocks and sudden changes in how people spend and borrow are very hard to see coming. In early 2022, the Bank of Canada's policy rate sat at 0.25%. By July 2023 it was 5%. Some people saw tightening ahead, but a household that planned around low rates simply carrying on got a very different few years than it budgeted for.
None of this makes forecasts useless. They are conditional statements, and agreement can make a conditional outlook feel more dependable than it really is. So the better question at renewal is whether your mortgage decision needs the economists to be right.
How to choose a mortgage that survives a wrong forecast
A mortgage plan should work even when the rate forecast is wrong. Three habits put that into practice.
Ask what has to happen for the forecast to hold. Behind every "rates will fall" sits a chain of conditions, such as inflation continuing to ease or growth weakening. Once you name those conditions, you can see the forecast as a bet on them. It also helps to know which rate a forecast is about. Variable mortgage rates generally follow lenders' prime rates, which move with Bank of Canada decisions. Fixed rates are shaped more by Government of Canada bond yields and lenders' own funding costs. A forecast for the policy rate is not a quote for a five-year fixed.
Run three payment scenarios on the same loan. Keep the balance and remaining amortization fixed, and change only the rate. As an illustration, take a $500,000 balance over 25 years. At 4%, the monthly payment is roughly $2,630. At 5%, it's about $2,908. At 6%, it's about $3,199. These are planning tests, not predictions. If you're renewing, ask whether the higher line still fits your household budget. If you're buying, ask whether it still sits inside the payment you'd call comfortable. If you own a rental, ask whether the rent still covers it with room for repairs and vacancy. Lenders apply a version of this test already: uninsured borrowers must qualify at the higher of their contract rate plus 2 percentage points or 5.25%. Your own test should reflect your real life, beyond simply clearing the lender's bar.
Price flexibility alongside the rate. Compare total borrowing cost over the term, including what it would cost to leave early and what prepayment room you'd have. Variable-rate penalties are commonly three months' interest. Fixed-rate penalties can be much larger, depending on the lender and how they calculate them. A slightly lower quoted rate can turn out expensive if you need to sell, refinance or restructure partway through.
A good decision and a correct prediction are separate achievements, and you only need the first. You don't have to outguess economists to protect your finances. Before you sign, check whether the mortgage you're considering still fits if the expected rate relief never arrives. Use forecasts to inform your plan, but make sure your plan stays affordable without them.

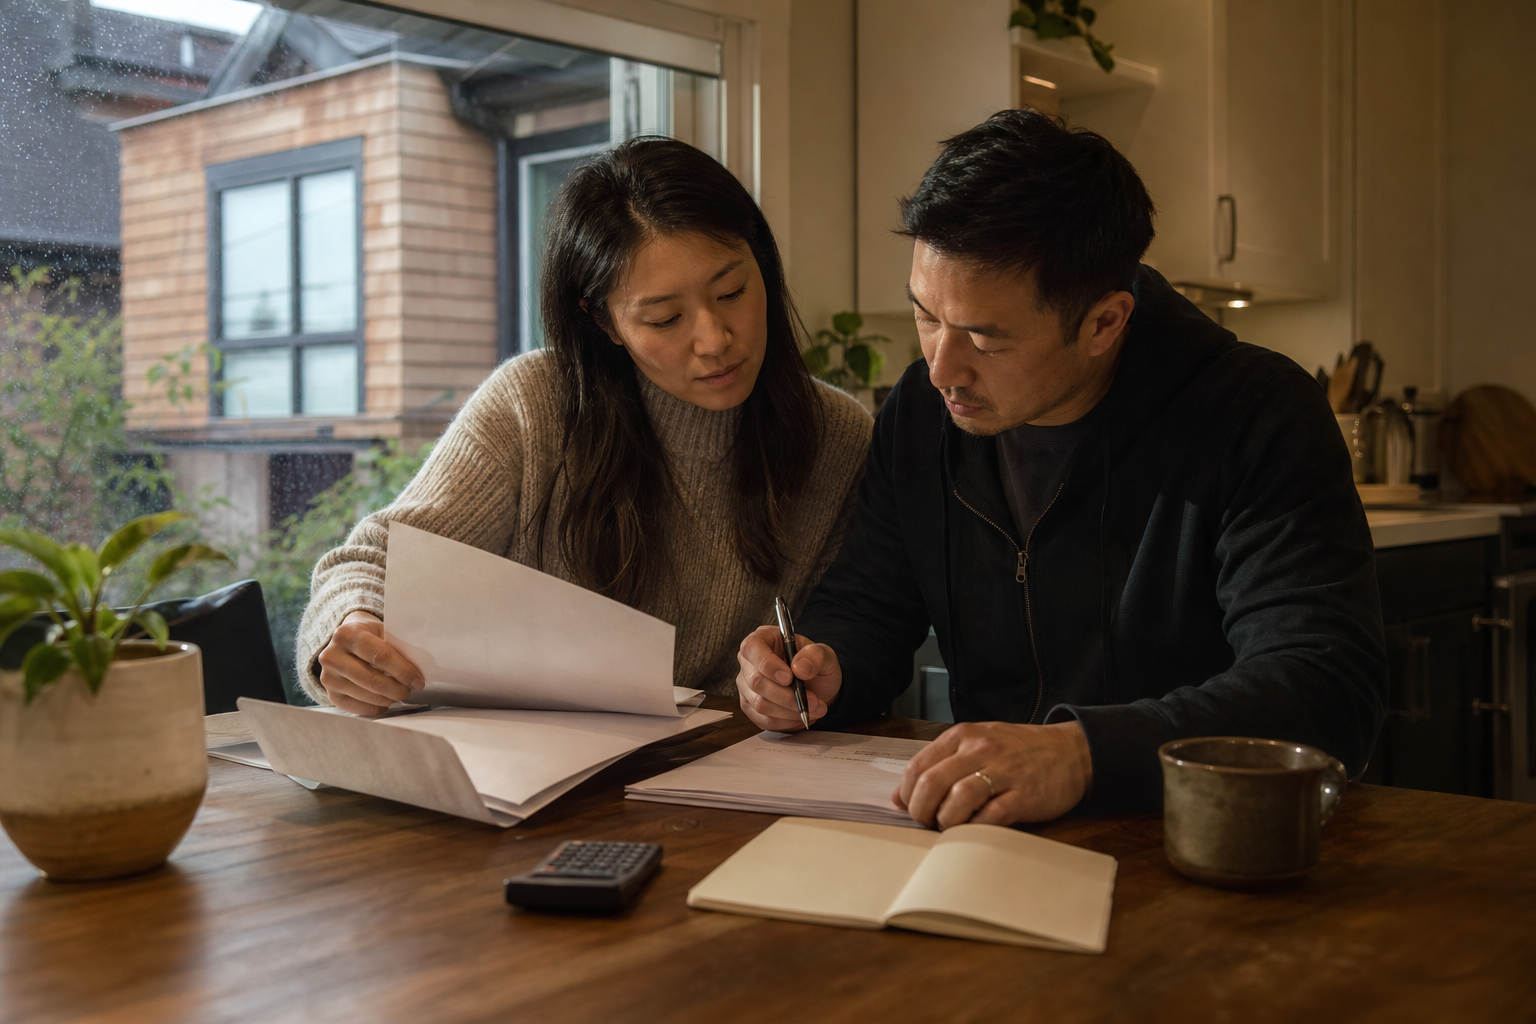
A mortgage renewal letter doesn't wait for the forecasts to settle. It arrives with a date, a balance and a decision, while the headlines around it say rates should ease, probably, by next year. That reassurance is pleasant to read, but a forecast that rates will fall doesn't tell you what payment your household can safely carry if they don't. Learning to use forecasts without leaning your budget on them is one of the most useful skills a borrower can have.
If you've compared mortgage options while several forecasts promised lower rates, you know the feeling: you're signing something firm on the strength of something soft. Homeowners renewing across British Columbia feel it. So do first-time buyers deciding whether to wait for relief, and rental-property owners trying to keep a thin monthly margin from turning negative.
Why agreement does not make a rate forecast safer
When five bank economists publish similar outlooks, it can look like five separate confirmations. Usually it is closer to one view expressed five ways. Forecasters draw on the same inflation, employment and growth releases, and they often share the same assumptions about how the economy will respond. There is also a quiet professional incentive at work: being wrong alongside everyone else costs a forecaster far less than being wrong alone. So outlooks tend to cluster, and when the shared assumption breaks, they tend to miss together.
The data itself has limits. Published figures describe a period that has already passed, and they can be revised after the fact. Good forecasters also use forward-looking information, such as market pricing and surveys. Still, shocks and sudden changes in how people spend and borrow are very hard to see coming. In early 2022, the Bank of Canada's policy rate sat at 0.25%. By July 2023 it was 5%. Some people saw tightening ahead, but a household that planned around low rates simply carrying on got a very different few years than it budgeted for.
None of this makes forecasts useless. They are conditional statements, and agreement can make a conditional outlook feel more dependable than it really is. So the better question at renewal is whether your mortgage decision needs the economists to be right.
How to choose a mortgage that survives a wrong forecast
A mortgage plan should work even when the rate forecast is wrong. Three habits put that into practice.
Ask what has to happen for the forecast to hold. Behind every "rates will fall" sits a chain of conditions, such as inflation continuing to ease or growth weakening. Once you name those conditions, you can see the forecast as a bet on them. It also helps to know which rate a forecast is about. Variable mortgage rates generally follow lenders' prime rates, which move with Bank of Canada decisions. Fixed rates are shaped more by Government of Canada bond yields and lenders' own funding costs. A forecast for the policy rate is not a quote for a five-year fixed.
Run three payment scenarios on the same loan. Keep the balance and remaining amortization fixed, and change only the rate. As an illustration, take a $500,000 balance over 25 years. At 4%, the monthly payment is roughly $2,630. At 5%, it's about $2,908. At 6%, it's about $3,199. These are planning tests, not predictions. If you're renewing, ask whether the higher line still fits your household budget. If you're buying, ask whether it still sits inside the payment you'd call comfortable. If you own a rental, ask whether the rent still covers it with room for repairs and vacancy. Lenders apply a version of this test already: uninsured borrowers must qualify at the higher of their contract rate plus 2 percentage points or 5.25%. Your own test should reflect your real life, beyond simply clearing the lender's bar.
Price flexibility alongside the rate. Compare total borrowing cost over the term, including what it would cost to leave early and what prepayment room you'd have. Variable-rate penalties are commonly three months' interest. Fixed-rate penalties can be much larger, depending on the lender and how they calculate them. A slightly lower quoted rate can turn out expensive if you need to sell, refinance or restructure partway through.
A good decision and a correct prediction are separate achievements, and you only need the first. You don't have to outguess economists to protect your finances. Before you sign, check whether the mortgage you're considering still fits if the expected rate relief never arrives. Use forecasts to inform your plan, but make sure your plan stays affordable without them.
Read Next
Why Waiting for Mortgage Rates to Drop Will Probably Cost You More
Refinance Early to Escape Market Uncertainty or Ride Out Your Term? Here's Who Each One Is For
Why That Tiny Housing Uptick Gives You the Upper Hand
Buying in the Cold: 4 Steps to Protect Your Cash Flow Before You Sign