Fifteen-plus years of BC mortgage experience, distilled into practical writing on buying, renewing, refinancing, and building wealth through real estate.
Why Waiting for Mortgage Rates to Drop Will Probably Cost You More
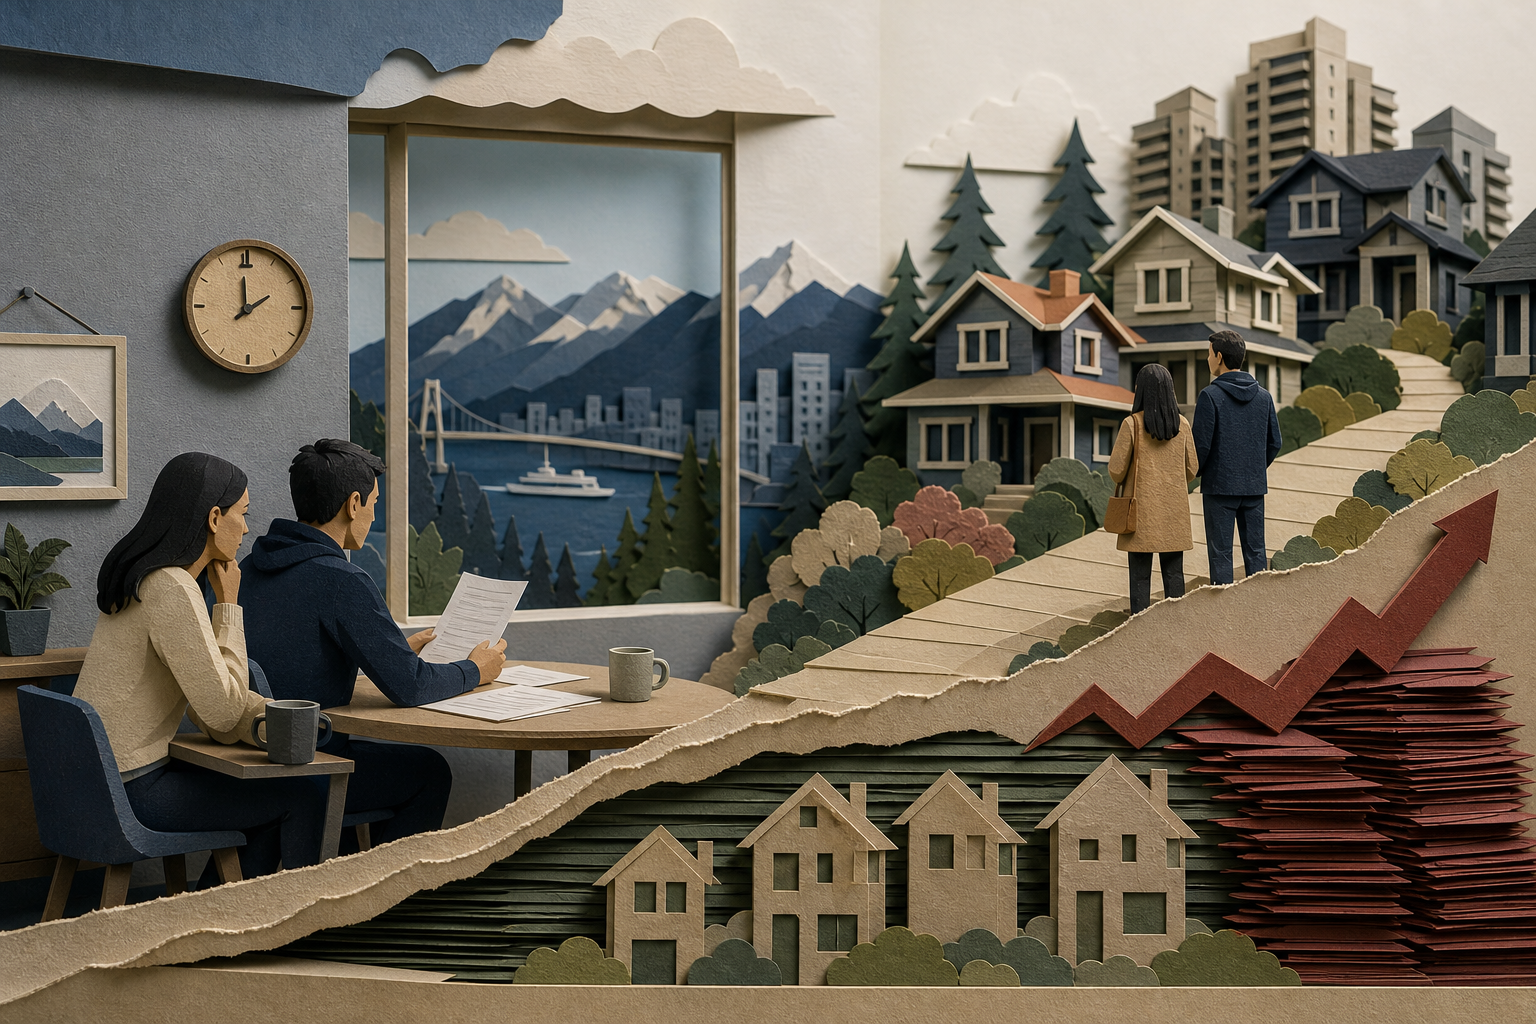
You sit down on a Sunday evening, scroll through active listings, and tell yourself the same thing you said last month: let's wait until borrowing costs come down.
It sounds like the responsible move. Why take on a mortgage today when rates might be softer down the road? It feels safer to keep your money parked, stay patient, and let things settle.
Except the market is not following that script.
The Missing Price Drop
Traditional economic thinking says that when borrowing costs go up, home prices should soften to balance things out. If money is more expensive to borrow, buyers can afford less, and sellers are forced to adjust.
Yet in October, Canada's housing market ticked up slightly even as borrowing costs rose. Both sales and prices edged higher.
A strong place to look for why this happens is the structural supply shortage. Across the country, there simply are not enough homes available to satisfy basic demand. That shortage continues to overpower higher borrowing costs, defying what standard market expectations say should happen.
If prices are already creeping higher while debt is expensive, sitting on the sidelines carries a quiet cost that many buyers overlook.
The Double Squeeze on the Sidelines
When you pause your search to wait for cheaper debt, you risk getting squeezed from two directions at once.
First, you pay higher prices right now. If scarce supply keeps nudging home values up month after month, the home you want today will cost more tomorrow, regardless of where rates sit.
Second, you face the crowd the moment borrowing costs finally do ease. The minute rates drop, thousands of buyers who spent months waiting beside you will jump back into the market on the exact same weekend.
That sudden rush of demand brings back fierce bidding wars. Sellers regain all their pricing power, buyers feel pressured to strip out basic safety clauses just to compete, and any savings you hoped to gain on your monthly interest rate get swallowed whole by a higher purchase price.
You end up trading a slightly lower rate for a higher purchase price and a far more stressful buying process.
The Supply-First Strategy
Instead of trying to time where interest rates are heading, you can build your plan around how supply actually behaves. I call this the Supply-First Strategy.
It shifts your attention away from interest rate forecasts and focuses on taking advantage of current market conditions while protecting your household budget.
Here are four practical moves to put this into practice:
Underwrite strictly to your cash flow today. Never buy a home on the hope that future rate cuts will make your monthly payments manageable. Build your purchase budget entirely around what your household income comfortably supports right now. If the payment fits your life today, your family is secure no matter what the market does next.
Keep your conditions firmly in every offer. When the market is moving at a measured pace, you have the room to protect yourself. Use this environment to keep your financing and home inspection conditions intact. You get the time to verify the property and review the paperwork without feeling forced into a rushed, unconditional offer.
Use short-term or flexible debt. Buying today does not mean locking yourself into rigid terms for five years. By structuring your mortgage into shorter or more flexible terms, you secure the property at today's price while keeping the door open to capture future rate cuts as they arrive.
Keep a rolling 120-day rate hold active. Rate fluctuations can create unnecessary stress while you shop. Keeping an active 120-day rate hold in place protects your approval so unexpected shifts in borrowing costs do not alter your budget in the middle of your home search.
Moving on Your Own Terms
Waiting for the market to give you the perfect combination of rock-bottom rates and soft prices is a gamble that rarely pays off. When rates drop, competition returns, and supply shortages make sure sellers hold the upper hand.
By buying when the pace is steady, protecting your cash flow, and structuring your debt to capture future drops, you get to buy on your terms instead of competing on everyone else's.

You sit down on a Sunday evening, scroll through active listings, and tell yourself the same thing you said last month: let's wait until borrowing costs come down.
It sounds like the responsible move. Why take on a mortgage today when rates might be softer down the road? It feels safer to keep your money parked, stay patient, and let things settle.
Except the market is not following that script.
The Missing Price Drop
Traditional economic thinking says that when borrowing costs go up, home prices should soften to balance things out. If money is more expensive to borrow, buyers can afford less, and sellers are forced to adjust.
Yet in October, Canada's housing market ticked up slightly even as borrowing costs rose. Both sales and prices edged higher.
A strong place to look for why this happens is the structural supply shortage. Across the country, there simply are not enough homes available to satisfy basic demand. That shortage continues to overpower higher borrowing costs, defying what standard market expectations say should happen.
If prices are already creeping higher while debt is expensive, sitting on the sidelines carries a quiet cost that many buyers overlook.
The Double Squeeze on the Sidelines
When you pause your search to wait for cheaper debt, you risk getting squeezed from two directions at once.
First, you pay higher prices right now. If scarce supply keeps nudging home values up month after month, the home you want today will cost more tomorrow, regardless of where rates sit.
Second, you face the crowd the moment borrowing costs finally do ease. The minute rates drop, thousands of buyers who spent months waiting beside you will jump back into the market on the exact same weekend.
That sudden rush of demand brings back fierce bidding wars. Sellers regain all their pricing power, buyers feel pressured to strip out basic safety clauses just to compete, and any savings you hoped to gain on your monthly interest rate get swallowed whole by a higher purchase price.
You end up trading a slightly lower rate for a higher purchase price and a far more stressful buying process.
The Supply-First Strategy
Instead of trying to time where interest rates are heading, you can build your plan around how supply actually behaves. I call this the Supply-First Strategy.
It shifts your attention away from interest rate forecasts and focuses on taking advantage of current market conditions while protecting your household budget.
Here are four practical moves to put this into practice:
Moving on Your Own Terms
Waiting for the market to give you the perfect combination of rock-bottom rates and soft prices is a gamble that rarely pays off. When rates drop, competition returns, and supply shortages make sure sellers hold the upper hand.
By buying when the pace is steady, protecting your cash flow, and structuring your debt to capture future drops, you get to buy on your terms instead of competing on everyone else's.
Read Next
Refinance Early to Escape Market Uncertainty or Ride Out Your Term? Here's Who Each One Is For
Why That Tiny Housing Uptick Gives You the Upper Hand
Buying in the Cold: 4 Steps to Protect Your Cash Flow Before You Sign
The Housing Market Isn't the Only Place Your Money Can Grow