Fifteen-plus years of BC mortgage experience, distilled into practical writing on buying, renewing, refinancing, and building wealth through real estate.
Walking Away From Your Mortgage Works Differently in Canada Than You Think
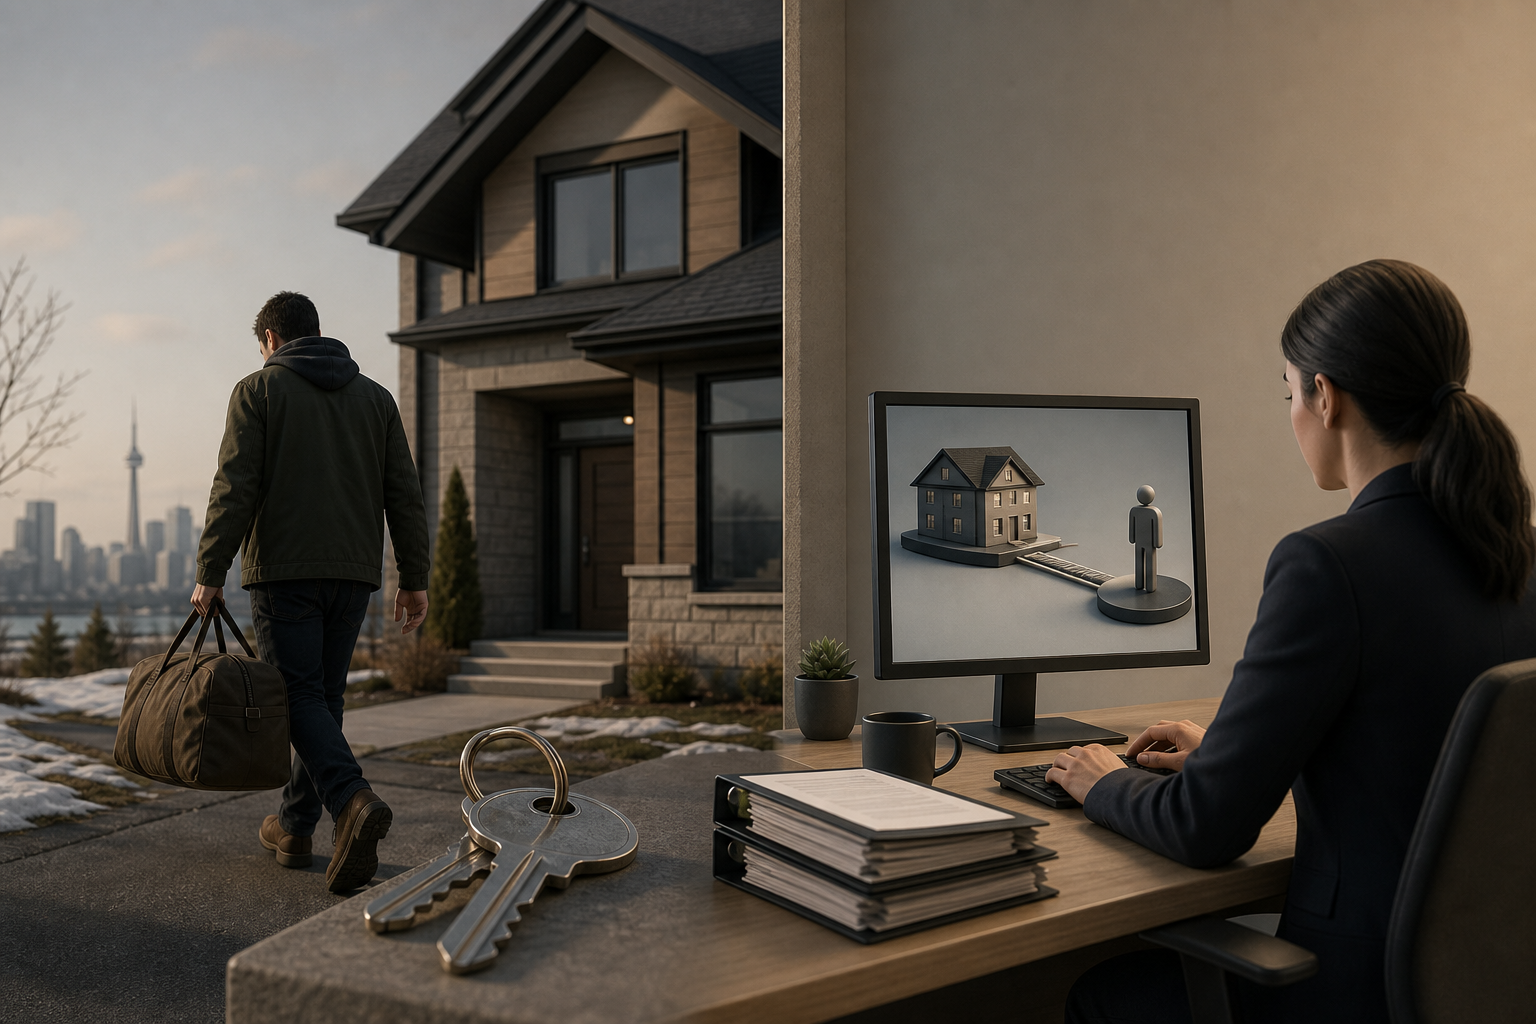
The 2008 housing crash taught Americans they could mail their house keys to the bank and walk away. Canadian homeowners who watched that unfold often believe the same rules apply here. They don't, and the difference will cost you more than the house.
In most U.S. states hit hardest by the crash, California, Arizona, Nevada, mortgage loans were non-recourse. If you owed $400,000 on a home now worth $250,000, you could hand over the keys, take the credit hit, and the lender absorbed the loss. The debt died with the house. Canadians saw this on the news and assumed "strategic default" worked the same way everywhere.
It doesn't. Canada operates almost entirely under recourse lending. When a lender forecloses or exercises Power of Sale and sells your home for less than you owe, they don't write off the difference. They sue you for it. That shortfall becomes an unsecured judgment, enforceable through wage garnishment, asset seizure, or a lien on any future property you buy. Walking away from the house does not walk away from the debt. It just turns secured debt into a legal claim that follows you.
Alberta and Saskatchewan Are the Only Exceptions, Barely
Alberta's Land Titles Act makes certain residential mortgages non-recourse, but only if they're conventional loans (20% down or more) on your primary residence. If you refinanced, took out a HELOC, or the loan was high-ratio and CMHC-insured, you lose that protection. Saskatchewan has similar carve-outs under the Limitation of Civil Rights Act, but they're narrow. Most Canadian mortgages, even in these provinces, remain recourse.
Everywhere else, Ontario, B.C., Quebec, the Atlantic provinces, the lender can and will pursue the deficiency. In Ontario, the standard process is Power of Sale, which is faster than full foreclosure. The lender sells the property without taking formal title, but you remain on the hook for the gap between sale price and what you owed, plus legal fees and selling costs. Those fees routinely add $20,000 to $50,000 to the debt.
CMHC Insurance Doesn't Protect You
If your mortgage is insured by CMHC, Sagen, or Canada Guaranty, common for buyers who put down less than 20%, the mechanics change but the outcome for you gets worse. The lender files a claim with the insurer and gets paid in full. That sounds like relief until you realize the insurer now owns the debt and has specialized recovery teams whose only job is to collect from you. CMHC does not forgive. It reimburses the bank, then comes after the borrower.
Walking away also destroys your credit for six to seven years under current reporting standards. A foreclosure or Power of Sale stays on your file and blocks you from qualifying for car loans, business credit, even some rental applications. The mortgage is gone, but so is your ability to borrow for anything else.
The Trap of Negative Equity
Being underwater, owing more than the home is worth, does not by itself justify default in Canada the way it sometimes did in the U.S. If you stop paying, the process grinds forward: missed payments, demand letters, Notice of Sale, court filings, eventual sale. The lender has a duty to obtain fair market value, but in a down market that's still less than you owe. You're left holding a five- or six-figure unsecured debt with a wrecked credit file.
Some borrowers avoid formal foreclosure by selling at a loss and covering the shortfall with an unsecured line of credit or family loan. It keeps the debt but saves the credit score. Others file a consumer proposal through a Licensed Insolvency Trustee, which restructures the debt and avoids full bankruptcy. The Office of the Superintendent of Bankruptcy reported rising use of proposals in 2025 as homeowners in rate-shock situations sought alternatives to default.
Strategic default, choosing not to pay because the asset is worth less than the loan, makes financial sense only in true non-recourse markets. In Canada, it converts one problem into two: you lose the house and inherit an enforceable judgment. The system is designed to keep you paying.

The 2008 housing crash taught Americans they could mail their house keys to the bank and walk away. Canadian homeowners who watched that unfold often believe the same rules apply here. They don't, and the difference will cost you more than the house.
In most U.S. states hit hardest by the crash, California, Arizona, Nevada, mortgage loans were non-recourse. If you owed $400,000 on a home now worth $250,000, you could hand over the keys, take the credit hit, and the lender absorbed the loss. The debt died with the house. Canadians saw this on the news and assumed "strategic default" worked the same way everywhere.
It doesn't. Canada operates almost entirely under recourse lending. When a lender forecloses or exercises Power of Sale and sells your home for less than you owe, they don't write off the difference. They sue you for it. That shortfall becomes an unsecured judgment, enforceable through wage garnishment, asset seizure, or a lien on any future property you buy. Walking away from the house does not walk away from the debt. It just turns secured debt into a legal claim that follows you.
Alberta and Saskatchewan Are the Only Exceptions, Barely
Alberta's Land Titles Act makes certain residential mortgages non-recourse, but only if they're conventional loans (20% down or more) on your primary residence. If you refinanced, took out a HELOC, or the loan was high-ratio and CMHC-insured, you lose that protection. Saskatchewan has similar carve-outs under the Limitation of Civil Rights Act, but they're narrow. Most Canadian mortgages, even in these provinces, remain recourse.
Everywhere else, Ontario, B.C., Quebec, the Atlantic provinces, the lender can and will pursue the deficiency. In Ontario, the standard process is Power of Sale, which is faster than full foreclosure. The lender sells the property without taking formal title, but you remain on the hook for the gap between sale price and what you owed, plus legal fees and selling costs. Those fees routinely add $20,000 to $50,000 to the debt.
CMHC Insurance Doesn't Protect You
If your mortgage is insured by CMHC, Sagen, or Canada Guaranty, common for buyers who put down less than 20%, the mechanics change but the outcome for you gets worse. The lender files a claim with the insurer and gets paid in full. That sounds like relief until you realize the insurer now owns the debt and has specialized recovery teams whose only job is to collect from you. CMHC does not forgive. It reimburses the bank, then comes after the borrower.
Walking away also destroys your credit for six to seven years under current reporting standards. A foreclosure or Power of Sale stays on your file and blocks you from qualifying for car loans, business credit, even some rental applications. The mortgage is gone, but so is your ability to borrow for anything else.
The Trap of Negative Equity
Being underwater, owing more than the home is worth, does not by itself justify default in Canada the way it sometimes did in the U.S. If you stop paying, the process grinds forward: missed payments, demand letters, Notice of Sale, court filings, eventual sale. The lender has a duty to obtain fair market value, but in a down market that's still less than you owe. You're left holding a five- or six-figure unsecured debt with a wrecked credit file.
Some borrowers avoid formal foreclosure by selling at a loss and covering the shortfall with an unsecured line of credit or family loan. It keeps the debt but saves the credit score. Others file a consumer proposal through a Licensed Insolvency Trustee, which restructures the debt and avoids full bankruptcy. The Office of the Superintendent of Bankruptcy reported rising use of proposals in 2025 as homeowners in rate-shock situations sought alternatives to default.
Strategic default, choosing not to pay because the asset is worth less than the loan, makes financial sense only in true non-recourse markets. In Canada, it converts one problem into two: you lose the house and inherit an enforceable judgment. The system is designed to keep you paying.
Read Next
Canada Lost 55,000 People This Quarter, So Why Aren't Home Prices Following?
CRA's New Billion-Dollar Ruling Program: How to Lock in Tax Certainty Before You Build
Why Porting Your 2.7% Mortgage Could Cost You $47,000 More Than Breaking It
Why Your Mortgage Renewal Is Making Crypto Look Smart (And What That Tells You)