Fifteen-plus years of BC mortgage experience, distilled into practical writing on buying, renewing, refinancing, and building wealth through real estate.
Canada Lost 55,000 People This Quarter, So Why Aren't Home Prices Following?
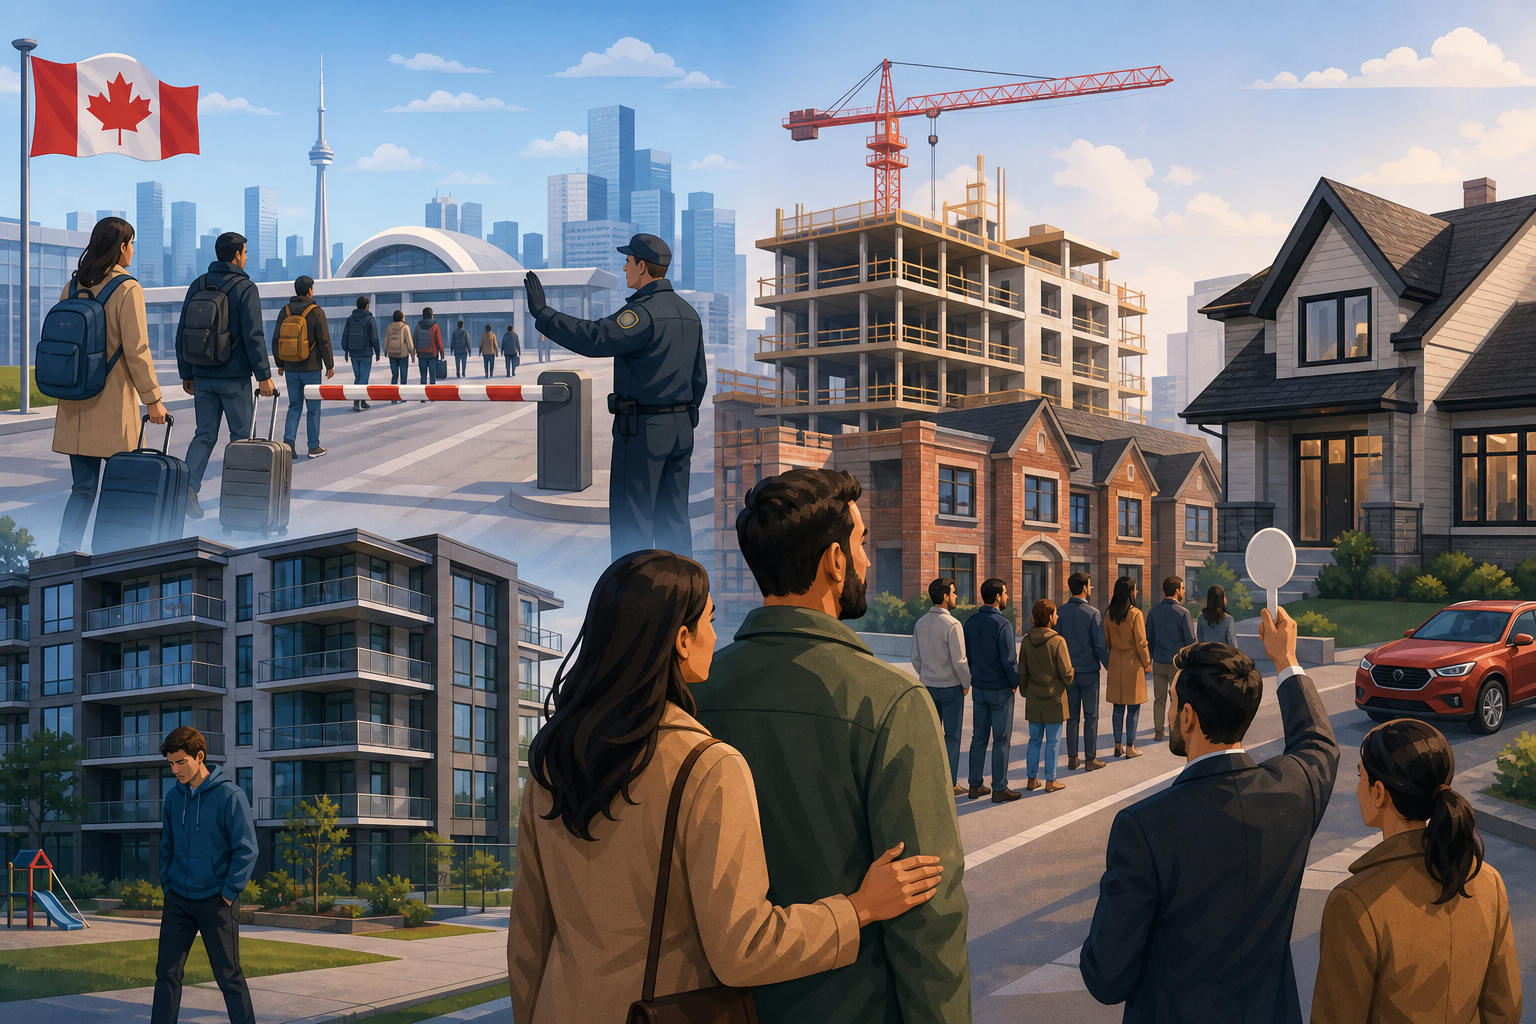
Statistics Canada logged a 55,025-person drop between January and April 2026, the third consecutive quarterly decline. The national average home price in August sat at $668,219, down marginally from July but nowhere near the correction you'd expect if supply-and-demand textbooks ruled the market cleanly.
The population loss is real and it's policy-driven. Ottawa cut both permanent resident targets and non-permanent resident inflows, international students, temporary foreign workers, the cohort that drove population growth before policy restrictions took effect. That growth rate strained housing, transit, and public services so badly that economists warned of a "population trap" where construction and staff couldn't keep pace. The decline is the intended result of cooling that pressure.
But housing markets don't respond to population the way Econ 101 promises. The lag between demographic shifts and price movements runs twelve to twenty-four months. Lease cycles, construction timelines, and buyer sentiment all take time to adjust. More important, the 55,000-person drop is heavily concentrated in the non-permanent resident category, a renter-heavy demographic. The immediate impact shows up in rental vacancy rates, not resale home purchase competition.
The Backlog Problem
Canada entered this population slowdown with a massive housing deficit. CMHC estimated in prior years that the country needs 3.5 million additional units beyond current projections by 2030 just to restore affordability to historical norms. That shortfall didn't evaporate when the quarterly count ticked negative. Millions of Canadians in their twenties and thirties still live with parents or share apartments because forming an independent household remains unaffordable. This latent demand, households that want to exist but can't yet, means the number of people competing for housing can stay flat or even rise while the raw population count drops.
The mismatch extends to unit types. The decline doesn't solve the shortage of family-sized units: three-bedroom condos, townhomes, anything a household with children can actually occupy. Purpose-built rentals for students and temporary workers might see higher vacancy rates, but the missing middle, affordable ownership stock for domestic buyers, remains missing.
Interest Rates Are Doing More Work
The Bank of Canada's policy rate adjustments in late 2025 and early 2026 likely matter more to near-term pricing than a 0.1% population dip. When rates drop, sidelined buyers return. When they rise, demand cools regardless of how many people crossed the border. August 2026 national home sales came in at 37,504 units, down 0.7% month-over-month but shaped more by affordability and credit conditions than by net migration figures.
Regional divergence complicates the national story. Alberta continues to see inflows from Ontario and British Columbia as workers chase lower costs and tighter labor markets. A national average that shows slight decline can mask a Prairie boom and an Ontario stall. The GTA saw sales fall 2.1% year-over-year in August, but that's a demand softening, not a supply glut driven by fewer residents.
The Psychological Effect
News of a "declining population" may cool investor sentiment faster than it reduces actual competition. If buyers believe prices will fall, some delay purchases, which becomes a self-fulfilling softening. But that sentiment shifts when rates ease or when a wave of pent-up buyers decides the wait is over. The fundamentals, shortage, latent demand, tight labor market supporting wages, still point to constrained supply meeting persistent need.
Canada's population will likely stabilize rather than continue dropping. Natural increase is near zero; the country depends almost entirely on immigration for long-term economic stability. This decline reflects policy choices, not long-term demographic collapse. Housing prices will follow eventually, but the path runs through rental vacancies and construction cycles first, not through an immediate markdown at the resale counter.
Canadian Real Estate Association / Toronto Real Estate Board - The GTA saw sales fall 2.1% year-over-year in August - 2026-08-01. https://creastats.crea.ca/board/treb/

Statistics Canada logged a 55,025-person drop between January and April 2026, the third consecutive quarterly decline. The national average home price in August sat at $668,219, down marginally from July but nowhere near the correction you'd expect if supply-and-demand textbooks ruled the market cleanly.
The population loss is real and it's policy-driven. Ottawa cut both permanent resident targets and non-permanent resident inflows, international students, temporary foreign workers, the cohort that drove population growth before policy restrictions took effect. That growth rate strained housing, transit, and public services so badly that economists warned of a "population trap" where construction and staff couldn't keep pace. The decline is the intended result of cooling that pressure.
But housing markets don't respond to population the way Econ 101 promises. The lag between demographic shifts and price movements runs twelve to twenty-four months. Lease cycles, construction timelines, and buyer sentiment all take time to adjust. More important, the 55,000-person drop is heavily concentrated in the non-permanent resident category, a renter-heavy demographic. The immediate impact shows up in rental vacancy rates, not resale home purchase competition.
The Backlog Problem
Canada entered this population slowdown with a massive housing deficit. CMHC estimated in prior years that the country needs 3.5 million additional units beyond current projections by 2030 just to restore affordability to historical norms. That shortfall didn't evaporate when the quarterly count ticked negative. Millions of Canadians in their twenties and thirties still live with parents or share apartments because forming an independent household remains unaffordable. This latent demand, households that want to exist but can't yet, means the number of people competing for housing can stay flat or even rise while the raw population count drops.
The mismatch extends to unit types. The decline doesn't solve the shortage of family-sized units: three-bedroom condos, townhomes, anything a household with children can actually occupy. Purpose-built rentals for students and temporary workers might see higher vacancy rates, but the missing middle, affordable ownership stock for domestic buyers, remains missing.
Interest Rates Are Doing More Work
The Bank of Canada's policy rate adjustments in late 2025 and early 2026 likely matter more to near-term pricing than a 0.1% population dip. When rates drop, sidelined buyers return. When they rise, demand cools regardless of how many people crossed the border. August 2026 national home sales came in at 37,504 units, down 0.7% month-over-month but shaped more by affordability and credit conditions than by net migration figures.
Regional divergence complicates the national story. Alberta continues to see inflows from Ontario and British Columbia as workers chase lower costs and tighter labor markets. A national average that shows slight decline can mask a Prairie boom and an Ontario stall. The GTA saw sales fall 2.1% year-over-year in August, but that's a demand softening, not a supply glut driven by fewer residents.
The Psychological Effect
News of a "declining population" may cool investor sentiment faster than it reduces actual competition. If buyers believe prices will fall, some delay purchases, which becomes a self-fulfilling softening. But that sentiment shifts when rates ease or when a wave of pent-up buyers decides the wait is over. The fundamentals, shortage, latent demand, tight labor market supporting wages, still point to constrained supply meeting persistent need.
Canada's population will likely stabilize rather than continue dropping. Natural increase is near zero; the country depends almost entirely on immigration for long-term economic stability. This decline reflects policy choices, not long-term demographic collapse. Housing prices will follow eventually, but the path runs through rental vacancies and construction cycles first, not through an immediate markdown at the resale counter.
Sources
Read Next
CRA's New Billion-Dollar Ruling Program: How to Lock in Tax Certainty Before You Build
Why Porting Your 2.7% Mortgage Could Cost You $47,000 More Than Breaking It
Why Your Mortgage Renewal Is Making Crypto Look Smart (And What That Tells You)
Trade Uncertainty Changes What U.S. Dollar Exposure Actually Costs You