Fifteen-plus years of BC mortgage experience, distilled into practical writing on buying, renewing, refinancing, and building wealth through real estate.
Trade Uncertainty Changes What U.S. Dollar Exposure Actually Costs You
The 50% U.S. tariff on certain Canadian goods announced in August 2026 did something most investors didn't see coming. It didn't just change the cost of doing business across the border. It changed the math on every unhedged U.S. position in a Canadian portfolio.
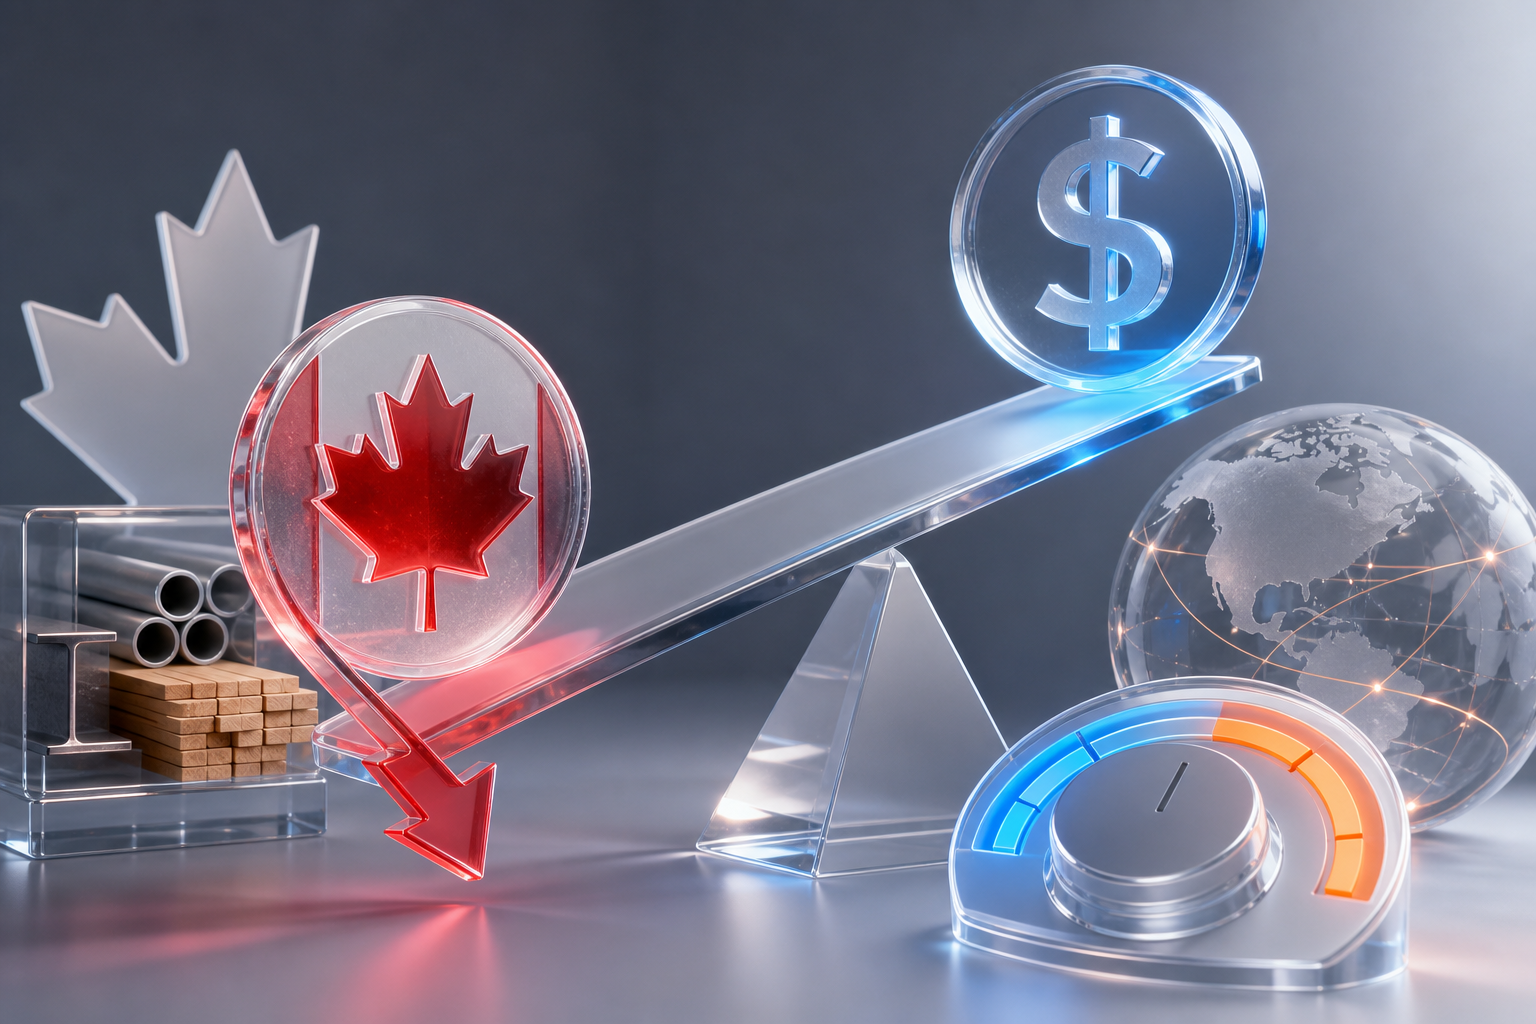
Most Canadian portfolios hold some U.S. dollar assets. For decades, that exposure functioned as ballast. When global markets sold off, capital flowed into USD and U.S. Treasuries. The currency move cushioned losses. But trade disruptions aimed specifically at Canada decouple the loonie from the broader safe-haven pattern. When Washington targets Canadian steel, aluminum, and softwood lumber, the CAD falls for reasons unrelated to oil prices or general risk appetite. The cushion becomes conditional.
The Safe Haven That Isn't Automatic
The classic case for USD exposure rests on negative correlation. Canadian equities fall during a global slowdown. The dollar strengthens. Your S&P 500 holdings lose value in USD terms but gain in CAD terms. The net effect softens the blow.
That logic holds when the shock is global. It breaks when the shock is bilateral. A tariff war between Canada and the U.S. is not a flight-to-quality event. It's a supply disruption that hits both economies differently. Canada, with 66% to 68% of its exports going to the U.S. and C$3.6 billion in daily cross-border goods trade, absorbs more of the damage. The CAD weakens. But USD strength in this case isn't a hedge, it's the market pricing in Canadian economic pain.
Between August 2026 and now, the CAD has moved in ways that look less like normal FX volatility and more like a risk premium. Investors holding unhedged U.S. equities saw portfolio values rise in domestic terms because the currency moved, not because their stocks performed well. Strip out the FX gain and many portfolios are flat or down.
What Hedging Actually Costs Now
Currency hedging for Canadian investors is priced on the interest rate differential between Canada and the U.S. When U.S. rates run higher, hedging USD back to CAD costs more. As of September 2026, that spread remains wide enough that full hedging eats 2% to 3% annually.
For a retiree drawing from a portfolio, that's real money. For an investor with a 20-year horizon, the question is whether that cost buys protection or just locks in underperformance. The answer depends on whether you believe the CAD will recover or continue weakening.
Historically, currencies revert to purchasing power parity over long periods. But ten years is long. And the CUSMA review milestone, passed in July 2026, remains a known catalyst for ongoing volatility. Markets price headline risk. Every speech, every negotiation leak, every threat to renegotiate terms moves the dollar. Investors face a choice: pay to hedge and eliminate that noise, or accept it as part of the return.
The Partial Hedge as a Dial
Most conversations about currency hedging treat it as binary. You hedge or you don't. But trade uncertainty makes the case for partial hedging stronger. A 50% hedge costs half as much and leaves you exposed to half the currency move. If trade tensions resolve and the CAD snaps back, you participate. If they worsen, you have some protection.
The tactical shift treats hedging as a dial you adjust month to month, not a switch you flip once. When trade headlines intensify, increase the hedge. When tensions ease, dial it back. This approach requires attention and some transaction cost, but it avoids the all-or-nothing trap where you either pay full freight for protection you might not need or take full risk you can't afford.
The Concentration You Didn't Plan
The other cost is concentration risk. Fleeing to USD during trade scares can leave you over-allocated to one currency and one economy. U.S. fiscal deficits, domestic inflation pressures, and long-term dollar dominance questions don't disappear because the CAD looks weak today.
Canadian institutional investors, pension funds managing tens of billions, have increased U.S. allocations for years to diversify away from the TSX's heavy tilt toward financials, energy, and materials. But retail investors often end up in the same trade for different reasons: because it feels safe when home feels uncertain. The result is a portfolio that's long USD by drift, not by design. You bought U.S. stocks for return and found yourself holding an outsized currency bet with no hedging plan to go with it.

The 50% U.S. tariff on certain Canadian goods announced in August 2026 did something most investors didn't see coming. It didn't just change the cost of doing business across the border. It changed the math on every unhedged U.S. position in a Canadian portfolio.
Most Canadian portfolios hold some U.S. dollar assets. For decades, that exposure functioned as ballast. When global markets sold off, capital flowed into USD and U.S. Treasuries. The currency move cushioned losses. But trade disruptions aimed specifically at Canada decouple the loonie from the broader safe-haven pattern. When Washington targets Canadian steel, aluminum, and softwood lumber, the CAD falls for reasons unrelated to oil prices or general risk appetite. The cushion becomes conditional.
The Safe Haven That Isn't Automatic
The classic case for USD exposure rests on negative correlation. Canadian equities fall during a global slowdown. The dollar strengthens. Your S&P 500 holdings lose value in USD terms but gain in CAD terms. The net effect softens the blow.
That logic holds when the shock is global. It breaks when the shock is bilateral. A tariff war between Canada and the U.S. is not a flight-to-quality event. It's a supply disruption that hits both economies differently. Canada, with 66% to 68% of its exports going to the U.S. and C$3.6 billion in daily cross-border goods trade, absorbs more of the damage. The CAD weakens. But USD strength in this case isn't a hedge, it's the market pricing in Canadian economic pain.
Between August 2026 and now, the CAD has moved in ways that look less like normal FX volatility and more like a risk premium. Investors holding unhedged U.S. equities saw portfolio values rise in domestic terms because the currency moved, not because their stocks performed well. Strip out the FX gain and many portfolios are flat or down.
What Hedging Actually Costs Now
Currency hedging for Canadian investors is priced on the interest rate differential between Canada and the U.S. When U.S. rates run higher, hedging USD back to CAD costs more. As of September 2026, that spread remains wide enough that full hedging eats 2% to 3% annually.
For a retiree drawing from a portfolio, that's real money. For an investor with a 20-year horizon, the question is whether that cost buys protection or just locks in underperformance. The answer depends on whether you believe the CAD will recover or continue weakening.
Historically, currencies revert to purchasing power parity over long periods. But ten years is long. And the CUSMA review milestone, passed in July 2026, remains a known catalyst for ongoing volatility. Markets price headline risk. Every speech, every negotiation leak, every threat to renegotiate terms moves the dollar. Investors face a choice: pay to hedge and eliminate that noise, or accept it as part of the return.
The Partial Hedge as a Dial
Most conversations about currency hedging treat it as binary. You hedge or you don't. But trade uncertainty makes the case for partial hedging stronger. A 50% hedge costs half as much and leaves you exposed to half the currency move. If trade tensions resolve and the CAD snaps back, you participate. If they worsen, you have some protection.
The tactical shift treats hedging as a dial you adjust month to month, not a switch you flip once. When trade headlines intensify, increase the hedge. When tensions ease, dial it back. This approach requires attention and some transaction cost, but it avoids the all-or-nothing trap where you either pay full freight for protection you might not need or take full risk you can't afford.
The Concentration You Didn't Plan
The other cost is concentration risk. Fleeing to USD during trade scares can leave you over-allocated to one currency and one economy. U.S. fiscal deficits, domestic inflation pressures, and long-term dollar dominance questions don't disappear because the CAD looks weak today.
Canadian institutional investors, pension funds managing tens of billions, have increased U.S. allocations for years to diversify away from the TSX's heavy tilt toward financials, energy, and materials. But retail investors often end up in the same trade for different reasons: because it feels safe when home feels uncertain. The result is a portfolio that's long USD by drift, not by design. You bought U.S. stocks for return and found yourself holding an outsized currency bet with no hedging plan to go with it.
Sources
Read Next
Canada Lost 55,000 People This Quarter, So Why Aren't Home Prices Following?
CRA's New Billion-Dollar Ruling Program: How to Lock in Tax Certainty Before You Build
Why Porting Your 2.7% Mortgage Could Cost You $47,000 More Than Breaking It
Why Your Mortgage Renewal Is Making Crypto Look Smart (And What That Tells You)