Fifteen-plus years of BC mortgage experience, distilled into practical writing on buying, renewing, refinancing, and building wealth through real estate.
RBC Calls It a Housing Recovery, But Recovery for Whom?
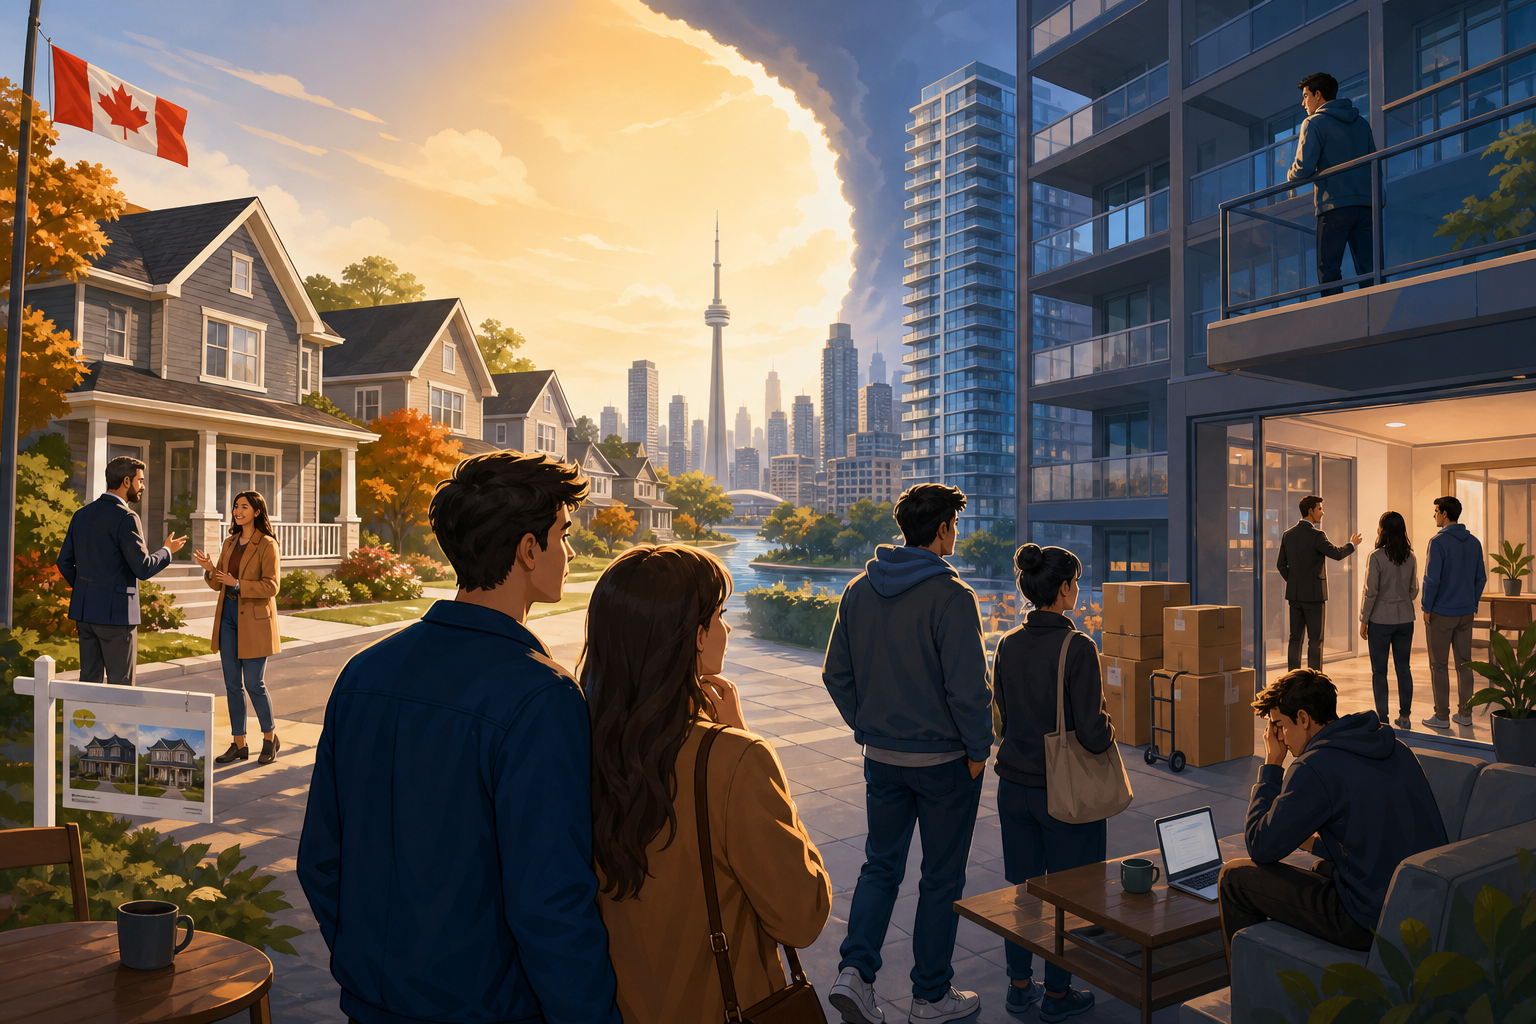
A Toronto buyer who sidelined themselves in 2024 waiting for rates to drop now faces a resale market where active listings have surged to multi-year highs while the Bank of Canada's policy rate sits substantially below the 5.00% peak of 2023. That buyer has more choice than they've had in years. They also have more competition, because everyone else who was waiting made the same call at the same time.
That's the shape of what RBC Economics is calling a housing recovery in 2026. Lower rates. Higher inventory. Prices stabilizing or creeping upward in most major markets. The sales-to-new-listings ratio moving back into balanced territory after spending most of 2024 deep in buyer's-market range. On paper, it's textbook normalization after the most aggressive monetary tightening cycle in decades.
The window narrows as you move up the ladder
For first-time buyers, the math improved. The qualifying rate dropped alongside market rates, increasing borrowing power by tens of thousands of dollars compared to 2024 levels. The mortgage stress test, which functions as the real affordability gate, eased enough that households previously shut out can now clear the hurdle. Renters who spent 2023 and 2024 watching their rent spike while homeownership felt impossible now see a narrow opening.
For move-up buyers, the recovery feels different. A household that bought in 2020 or 2021 at sub-2% rates is renewing in 2026 at something closer to 4%. That's a payment increase, sometimes a sharp one. The gap between what they locked in five years ago and what they're renewing into is large enough that the equity they've built doesn't fully offset the carrying cost shock. They can refinance out of the high fixed contracts signed in 2023 or 2024, yes, but the "recovery" for them is measured in hundreds of dollars per month they no longer have to allocate to the mortgage, not in newfound buying power.
The condo market in Toronto lags the detached recovery by six to nine months. High-density segments that saw the steepest declines in 2023 are barely stabilizing in 2026, while detached homes in the inner suburbs are already seeing modest year-over-year appreciation. That lag creates a value play for investors and first-timers willing to accept smaller square footage, but it also means the recovery isn't uniform even within a single metro.
Structural deficits don't care about sentiment
Canada's housing starts remain well below the 3.5 million additional units CMHC says the country needs by 2030. The "recovery" RBC describes is a sales recovery, a sentiment recovery, a return to transactional normalcy. It is not a supply recovery. The fundamental mismatch between household formation and new construction hasn't changed. The current window where rates have fallen but prices haven't fully regained their 2022 peak is narrow, and it's narrowing.
Alberta and Saskatchewan continue to lead price growth because their markets never reached the valuation extremes Ontario and BC did. A buyer in Calgary or Edmonton in 2026 is stepping into a market that looks more like 2019 elsewhere: functional, affordable relative to incomes, supplied well enough that inventory isn't the bottleneck. Ontario and BC are seeing volume recover faster than prices, which sounds like good news until you remember that volume without supply just resets the same scarcity dynamic that drove the last cycle.
The RBC report highlights a shift in market psychology, the sense that the floor is now firmly established. That's real. Buyer fear of missing out has returned in pockets. Sellers who waited out 2023 and 2024 are listing. The machinery of the market is working again.
Whether that machinery produces affordable outcomes for the median household is a different question entirely.

A Toronto buyer who sidelined themselves in 2024 waiting for rates to drop now faces a resale market where active listings have surged to multi-year highs while the Bank of Canada's policy rate sits substantially below the 5.00% peak of 2023. That buyer has more choice than they've had in years. They also have more competition, because everyone else who was waiting made the same call at the same time.
That's the shape of what RBC Economics is calling a housing recovery in 2026. Lower rates. Higher inventory. Prices stabilizing or creeping upward in most major markets. The sales-to-new-listings ratio moving back into balanced territory after spending most of 2024 deep in buyer's-market range. On paper, it's textbook normalization after the most aggressive monetary tightening cycle in decades.
The window narrows as you move up the ladder
For first-time buyers, the math improved. The qualifying rate dropped alongside market rates, increasing borrowing power by tens of thousands of dollars compared to 2024 levels. The mortgage stress test, which functions as the real affordability gate, eased enough that households previously shut out can now clear the hurdle. Renters who spent 2023 and 2024 watching their rent spike while homeownership felt impossible now see a narrow opening.
For move-up buyers, the recovery feels different. A household that bought in 2020 or 2021 at sub-2% rates is renewing in 2026 at something closer to 4%. That's a payment increase, sometimes a sharp one. The gap between what they locked in five years ago and what they're renewing into is large enough that the equity they've built doesn't fully offset the carrying cost shock. They can refinance out of the high fixed contracts signed in 2023 or 2024, yes, but the "recovery" for them is measured in hundreds of dollars per month they no longer have to allocate to the mortgage, not in newfound buying power.
The condo market in Toronto lags the detached recovery by six to nine months. High-density segments that saw the steepest declines in 2023 are barely stabilizing in 2026, while detached homes in the inner suburbs are already seeing modest year-over-year appreciation. That lag creates a value play for investors and first-timers willing to accept smaller square footage, but it also means the recovery isn't uniform even within a single metro.
Structural deficits don't care about sentiment
Canada's housing starts remain well below the 3.5 million additional units CMHC says the country needs by 2030. The "recovery" RBC describes is a sales recovery, a sentiment recovery, a return to transactional normalcy. It is not a supply recovery. The fundamental mismatch between household formation and new construction hasn't changed. The current window where rates have fallen but prices haven't fully regained their 2022 peak is narrow, and it's narrowing.
Alberta and Saskatchewan continue to lead price growth because their markets never reached the valuation extremes Ontario and BC did. A buyer in Calgary or Edmonton in 2026 is stepping into a market that looks more like 2019 elsewhere: functional, affordable relative to incomes, supplied well enough that inventory isn't the bottleneck. Ontario and BC are seeing volume recover faster than prices, which sounds like good news until you remember that volume without supply just resets the same scarcity dynamic that drove the last cycle.
The RBC report highlights a shift in market psychology, the sense that the floor is now firmly established. That's real. Buyer fear of missing out has returned in pockets. Sellers who waited out 2023 and 2024 are listing. The machinery of the market is working again.
Whether that machinery produces affordable outcomes for the median household is a different question entirely.
Read Next
Canada Lost 55,000 People This Quarter, So Why Aren't Home Prices Following?
CRA's New Billion-Dollar Ruling Program: How to Lock in Tax Certainty Before You Build
Why Porting Your 2.7% Mortgage Could Cost You $47,000 More Than Breaking It
Why Your Mortgage Renewal Is Making Crypto Look Smart (And What That Tells You)