Fifteen-plus years of BC mortgage experience, distilled into practical writing on buying, renewing, refinancing, and building wealth through real estate.
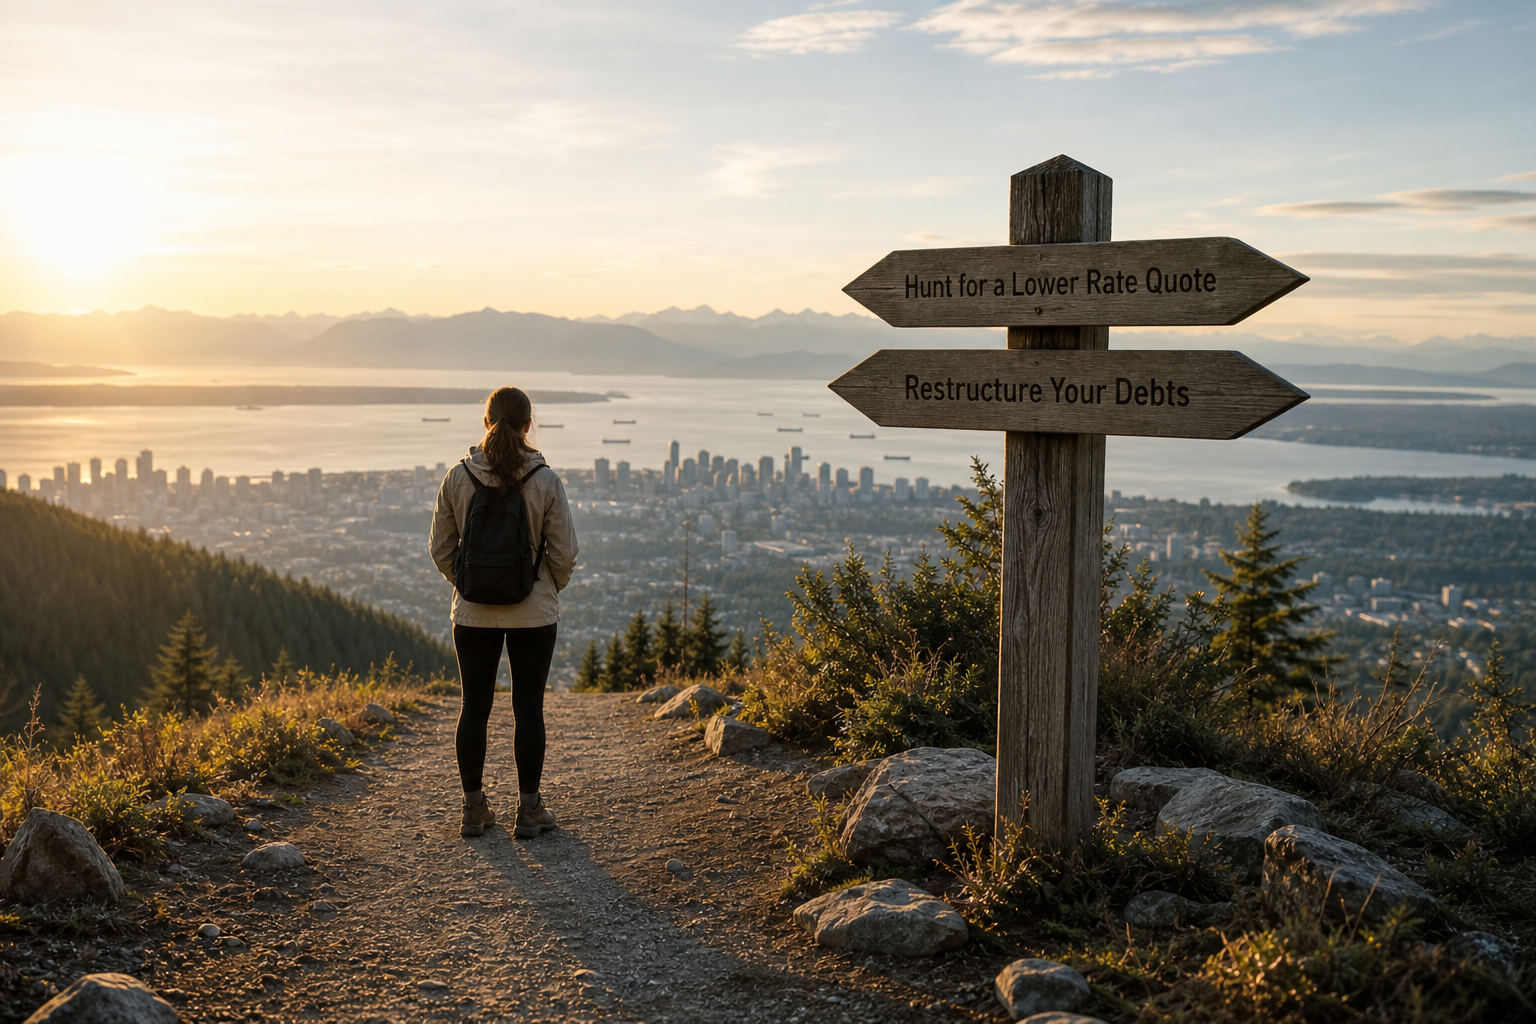
Hunt for a Lower Rate Quote or Restructure Your Debts? Here Is Who Each One Is For
Cutting twenty basis points off your mortgage quote feels like a win until you realize the bank still tests your income at the exact same number. When you are trying to buy in British Columbia and your numbers are tight, you generally have two ways to tackle the problem: chase a lower interest rate, or change the structure of your application. Both serve a purpose, but they solve completely different problems.
Option one: hunt for a lower contract rate
What it gives you: genuine cash-flow relief on your monthly mortgage payment once you take possession.
What it costs: weeks of your time. Shopping from lender to lender to trim a quarter of a point takes energy, and while you hunt, viable properties can pass you by.
Where it bites: the stress test floor. Underwriting guidelines qualify your income using your contract rate plus 2%, or the regulatory floor of 5.25%, whichever is higher. If your rate drops so low that contract plus 2% falls below that 5.25% mark, your purchasing power flatlines. The bank calculates your debt ratios against the exact same floor, meaning a lower quote gives you zero extra borrowing room.
Option two: restructure your debts and amortization
What it gives you: actual borrowing capacity. Paying off an outside monthly liability or lengthening your amortization period directly improves your debt-service ratios, which gives the bank room to approve a larger loan balance.
What it costs: cash upfront or a longer timeline. Wiping out a car loan or personal balance requires cash you might have wanted to keep in the bank, while extending your amortization means your balance takes longer to pay down.
Where it bites: your liquidity. Using cash to clear an existing debt leaves you with a smaller cushion after the purchase closes.
Who each one is for
Chasing a lower rate fits you if your debt-service ratios are already well within the bank's limits and your sole focus is keeping your regular monthly carrying costs as small as possible.
Restructuring liabilities and amortization fits you if you are stretching your borrowing limits to make a purchase work. Fractional rate cuts will not rescue tight debt ratios once you are underwritten at the floor, so your application needs structural changes instead.
The question that decides it
Are you trying to lower the payment you make every month, or are you hitting an approval wall with the bank? If you just want a cheaper monthly payment, negotiate the rate. If you are hitting an approval wall, stop waiting for a rate discount to fix it and look directly at your monthly debts and amortization.

Cutting twenty basis points off your mortgage quote feels like a win until you realize the bank still tests your income at the exact same number. When you are trying to buy in British Columbia and your numbers are tight, you generally have two ways to tackle the problem: chase a lower interest rate, or change the structure of your application. Both serve a purpose, but they solve completely different problems.
Option one: hunt for a lower contract rate
What it gives you: genuine cash-flow relief on your monthly mortgage payment once you take possession.
What it costs: weeks of your time. Shopping from lender to lender to trim a quarter of a point takes energy, and while you hunt, viable properties can pass you by.
Where it bites: the stress test floor. Underwriting guidelines qualify your income using your contract rate plus 2%, or the regulatory floor of 5.25%, whichever is higher. If your rate drops so low that contract plus 2% falls below that 5.25% mark, your purchasing power flatlines. The bank calculates your debt ratios against the exact same floor, meaning a lower quote gives you zero extra borrowing room.
Option two: restructure your debts and amortization
What it gives you: actual borrowing capacity. Paying off an outside monthly liability or lengthening your amortization period directly improves your debt-service ratios, which gives the bank room to approve a larger loan balance.
What it costs: cash upfront or a longer timeline. Wiping out a car loan or personal balance requires cash you might have wanted to keep in the bank, while extending your amortization means your balance takes longer to pay down.
Where it bites: your liquidity. Using cash to clear an existing debt leaves you with a smaller cushion after the purchase closes.
Who each one is for
Chasing a lower rate fits you if your debt-service ratios are already well within the bank's limits and your sole focus is keeping your regular monthly carrying costs as small as possible.
Restructuring liabilities and amortization fits you if you are stretching your borrowing limits to make a purchase work. Fractional rate cuts will not rescue tight debt ratios once you are underwritten at the floor, so your application needs structural changes instead.
The question that decides it
Are you trying to lower the payment you make every month, or are you hitting an approval wall with the bank? If you just want a cheaper monthly payment, negotiate the rate. If you are hitting an approval wall, stop waiting for a rate discount to fix it and look directly at your monthly debts and amortization.
Sources
Read Next
Why Waiting for Mortgage Rates to Drop Will Probably Cost You More
Refinance Early to Escape Market Uncertainty or Ride Out Your Term? Here's Who Each One Is For
Why That Tiny Housing Uptick Gives You the Upper Hand
Buying in the Cold: 4 Steps to Protect Your Cash Flow Before You Sign