Fifteen-plus years of BC mortgage experience, distilled into practical writing on buying, renewing, refinancing, and building wealth through real estate.
You land in Canada with $8,000, clean banking records from Hong Kong, and no debt. You apply for an apartment in Toronto. The landlord runs your name and comes back with: "No file found." Your credit score is not bad. It does not exist.
This is the newcomer trap. The same problem hits students applying for their first card and anyone who spent twenty years paying cash for everything. Canada's credit system does not reward debt-free living. It rewards a documented pattern of borrowing and repayment. If you have never borrowed here, you have no reputation, and no reputation looks identical to a bad one when the landlord, the cell phone carrier, or the car dealership pulls your report.
Building credit from zero takes six to twelve months if you follow the sequence correctly. Mess up the order and you add six more months of rejection letters.
Start with a secured credit card, not a regular one
You will be declined for a normal credit card. Apply anyway if you want to waste a hard inquiry and lower the score you don't have yet. The product that works is a secured card: you deposit $500 or $1,000, the bank holds it as collateral, and they issue you a card with a limit equal to the deposit. You are borrowing your own money, but the transaction gets reported to Equifax and TransUnion every 30 to 45 days as a tradeline.
Most of the big five banks offer this. The catch: a $500 limit turns into a problem fast if you're not careful. One $200 grocery run puts you at 40% utilization. Anything above 30% starts to hurt your score, even if you pay the balance in full. The fix is not to use the card less. The fix is to make two or three payments per month so the balance reported at statement close stays low. Pay $50 mid-cycle, another $50 before the statement cuts, then the remainder when the bill arrives.
Get a post-paid cell phone plan before the card arrives
Most people do this backward. Post-paid cell plans, Rogers, Bell, Telus, Fido, report to the credit bureaus. Prepaid plans do not. A $75/month post-paid plan with on-time payments for six months can establish enough history to generate your first score, sometimes faster than the secured card does because the cell contract starts reporting immediately.
The irony: you often need credit to get the post-paid plan. Some carriers waive this for newcomers if you put down a deposit. Others approve students with proof of enrollment. Call and ask what the workaround is. Do not assume the website policy is the final word.
Do not open three accounts in the same month
It is tempting to accelerate this by opening a secured card, a cell plan, and a retail store card all at once. You will tank your score before it exists. Each application is a hard inquiry. Three inquiries in thirty days signals desperation, and your average age of accounts, a factor worth roughly 15% of your score, starts at zero and stays there for months.
Open one account. Wait 90 days. Open the second. Wait another 90 days if you want a third. Boring works. Velocity does not.
Check which bureau your bank reports to and monitor that one
Equifax and TransUnion do not share data in Canada. A card that reports to Equifax only will build your Equifax file and leave your TransUnion file empty. Most major banks report to both, but not all credit unions and smaller lenders do. Call your issuer and confirm. Then sign up for free monitoring on the bureau they actually use. Most banking apps now offer this, TD and RBC integrate with TransUnion's CreditView, for example.
The timeline is this: first tradeline posts in 30 to 45 days, first score generates in four to six months, enough history to qualify for an unsecured card or a small loan in six to twelve months. That is the realistic version. Anything promising faster is selling you a shortcut that does not work.

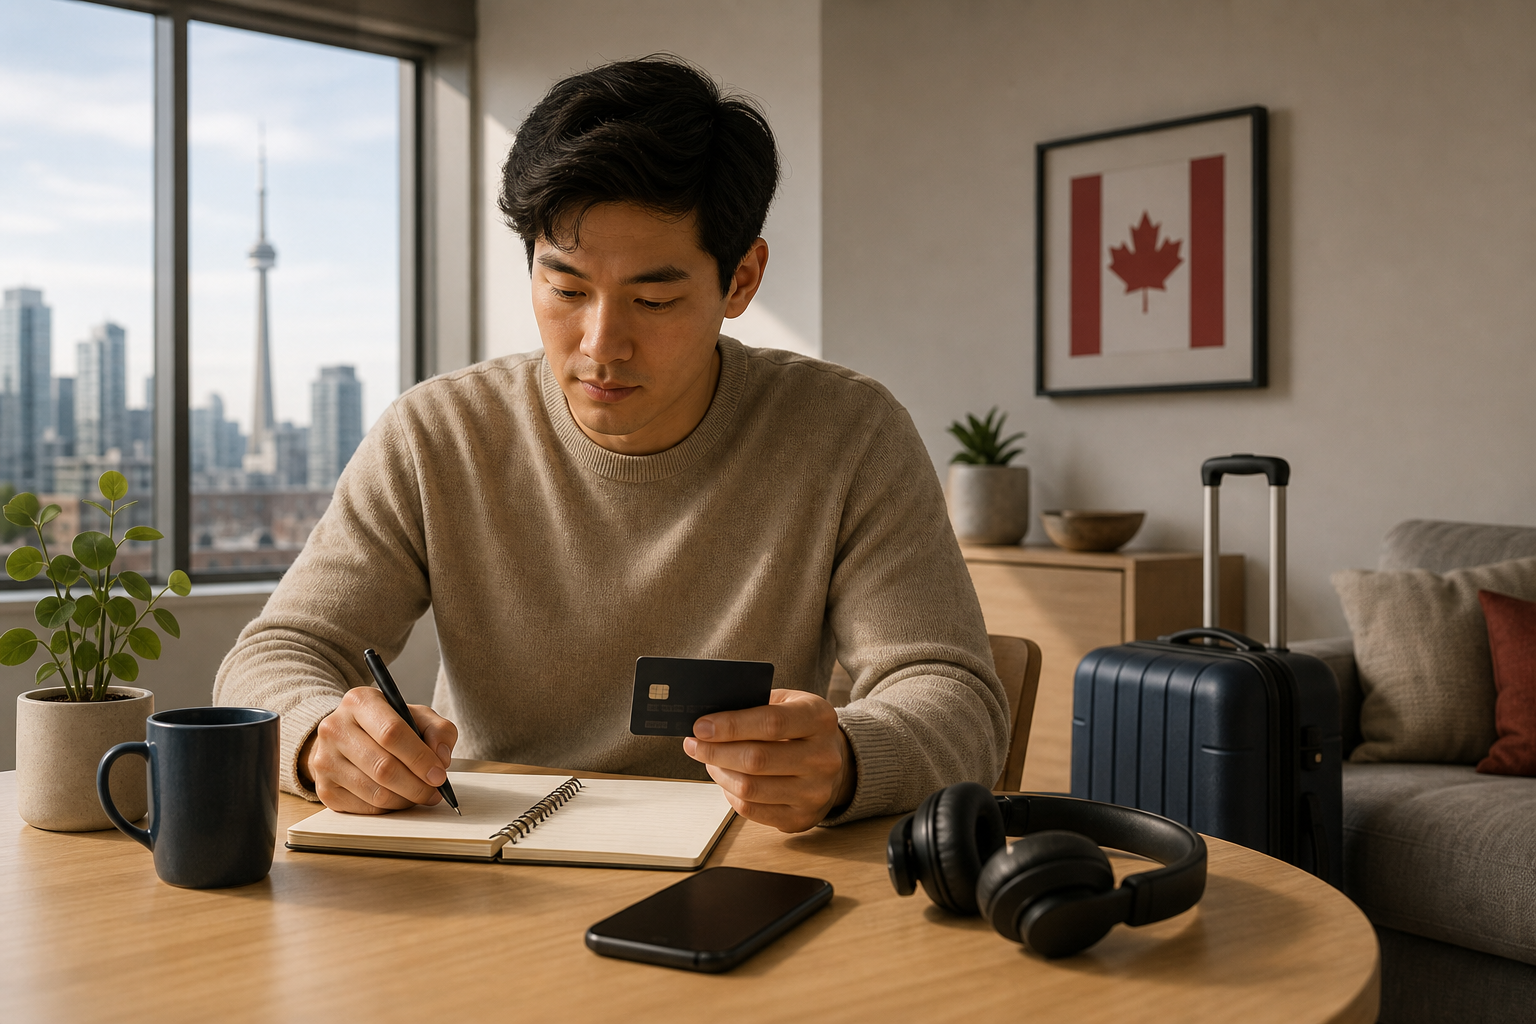
You land in Canada with $8,000, clean banking records from Hong Kong, and no debt. You apply for an apartment in Toronto. The landlord runs your name and comes back with: "No file found." Your credit score is not bad. It does not exist.
This is the newcomer trap. The same problem hits students applying for their first card and anyone who spent twenty years paying cash for everything. Canada's credit system does not reward debt-free living. It rewards a documented pattern of borrowing and repayment. If you have never borrowed here, you have no reputation, and no reputation looks identical to a bad one when the landlord, the cell phone carrier, or the car dealership pulls your report.
Building credit from zero takes six to twelve months if you follow the sequence correctly. Mess up the order and you add six more months of rejection letters.
Start with a secured credit card, not a regular one
You will be declined for a normal credit card. Apply anyway if you want to waste a hard inquiry and lower the score you don't have yet. The product that works is a secured card: you deposit $500 or $1,000, the bank holds it as collateral, and they issue you a card with a limit equal to the deposit. You are borrowing your own money, but the transaction gets reported to Equifax and TransUnion every 30 to 45 days as a tradeline.
Most of the big five banks offer this. The catch: a $500 limit turns into a problem fast if you're not careful. One $200 grocery run puts you at 40% utilization. Anything above 30% starts to hurt your score, even if you pay the balance in full. The fix is not to use the card less. The fix is to make two or three payments per month so the balance reported at statement close stays low. Pay $50 mid-cycle, another $50 before the statement cuts, then the remainder when the bill arrives.
Get a post-paid cell phone plan before the card arrives
Most people do this backward. Post-paid cell plans, Rogers, Bell, Telus, Fido, report to the credit bureaus. Prepaid plans do not. A $75/month post-paid plan with on-time payments for six months can establish enough history to generate your first score, sometimes faster than the secured card does because the cell contract starts reporting immediately.
The irony: you often need credit to get the post-paid plan. Some carriers waive this for newcomers if you put down a deposit. Others approve students with proof of enrollment. Call and ask what the workaround is. Do not assume the website policy is the final word.
Do not open three accounts in the same month
It is tempting to accelerate this by opening a secured card, a cell plan, and a retail store card all at once. You will tank your score before it exists. Each application is a hard inquiry. Three inquiries in thirty days signals desperation, and your average age of accounts, a factor worth roughly 15% of your score, starts at zero and stays there for months.
Open one account. Wait 90 days. Open the second. Wait another 90 days if you want a third. Boring works. Velocity does not.
Check which bureau your bank reports to and monitor that one
Equifax and TransUnion do not share data in Canada. A card that reports to Equifax only will build your Equifax file and leave your TransUnion file empty. Most major banks report to both, but not all credit unions and smaller lenders do. Call your issuer and confirm. Then sign up for free monitoring on the bureau they actually use. Most banking apps now offer this, TD and RBC integrate with TransUnion's CreditView, for example.
The timeline is this: first tradeline posts in 30 to 45 days, first score generates in four to six months, enough history to qualify for an unsecured card or a small loan in six to twelve months. That is the realistic version. Anything promising faster is selling you a shortcut that does not work.
Read Next
Canada Lost 55,000 People This Quarter, So Why Aren't Home Prices Following?
CRA's New Billion-Dollar Ruling Program: How to Lock in Tax Certainty Before You Build
Why Porting Your 2.7% Mortgage Could Cost You $47,000 More Than Breaking It
Why Your Mortgage Renewal Is Making Crypto Look Smart (And What That Tells You)