Fifteen-plus years of BC mortgage experience, distilled into practical writing on buying, renewing, refinancing, and building wealth through real estate.
How Canada-U.S. Trade Tensions Rewrite Mortgage Capacity and Tax Strategy for Cross-Border Earners
A software consultant in Vancouver invoices three U.S. clients who pay in USD. A manufacturer in Surrey ships 70 percent of output to Washington and Oregon. An investor in Burnaby holds a concentrated position in a TSX-listed company whose revenue is 80 percent American. All three passed mortgage stress tests in 2024. All three may fail the same test in 2026 if a tariff cycle cuts revenue by 15 percent or the Canadian dollar moves sharply in either direction.
Trade friction between Canada and the U.S. used to be something you read about in the business section and forgot by lunch. That assumption no longer holds. Tariff announcements, retaliatory measures, and currency swings now arrive with enough frequency and force to show up in cash flow statements, debt servicing ratios, and tax liabilities within a single fiscal year. For Canadians whose income or assets depend on cross-border trade flows, ignoring U.S. policy risk is no longer a defensible planning posture.
You don't need to predict whether tar Lenders see revenue concentration the moment they open your Notice of Assessment. When 60 percent or more of a business's income comes from U.S. sources, many underwriters treat that as elevated risk, regardless of gross margin. This matters in 2026 because the mortgage stress test already requires borrowers to qualify at the contract rate plus 200 basis points or 5.25 percent, whichever is higher. A business owner who clears that threshold under stable conditions may not clear it once the underwriter applies a discretionary haircut to projected income.
The haircut isn't written into OSFI guidelines. It appears in internal credit policy at individual lenders. A borrower whose T1 shows $180,000 in net business income might see that figure discounted to $153,000 if the underwriter decides cross-border exposure warrants a 15 percent reduction. For self-employed applicants, CMHC already applies a 15 percent gross-up to account for unreimbursed business expenses, but that adjustment moves in the borrower's favor. The trade-exposure discount moves against it, and the two do not offset. A borrower caught in both adjustments can lose 30 percent of stated income before the stress test even begins.
Why Currency Volatility Compounds the Problem
A weaker Canadian dollar should, in theory, help exporters. Revenue earned in USD converts to more CAD when the exchange rate moves from 1.35 to 1.42. But mortgage capacity depends on predictable income, and predictability breaks when the currency swings 5 percent in eight weeks. Lenders model income based on trailing twelve-month averages. A consultant who invoiced US$15,000 per month in 2024 and banked CAD$20,250 at an average rate of 1.35 will see September 2026 deposits of CAD$21,300 if the rate has moved to 1.42. That looks like growth. It isn't. The USD revenue stayed flat while the currency moved.
The reverse scenario is worse. If the CAD strengthens to 1.28 because trade tensions ease or commodity prices fall, the same US$15,000 converts to CAD$19,200. That consultant's stated income just dropped 5 percent without losing a single client. The mortgage underwriter sees declining revenue and may ask for additional reserves or a co-signer. Refinancing at renewal becomes harder. Switching lenders to chase a better rate may not be possible if the new lender recalculates income based on the most recent 24 months of financials, which now show a downward trend.
The Tax Treaty Doesn't Protect You from Operational Disruption
The Canada-U.S. Tax Treaty ensures you won't be taxed twice on the same income. It does not prevent a tariff from shrinking that income in the first place. A Surrey-based manufacturer who ships aluminum components to Oregon faced a 10 percent Section 232 tariff in 2018 and paid it by accepting thinner margins. When the U.S. Department of Commerce increased the all-others rate on Canadian softwood lumber to nearly double the prior level in 2024, British Columbia producers had three options: eat the cost, raise prices and lose orders, or exit certain product lines. None of those paths preserve the income level your tax return showed last year.
Tariffs also disrupt the timing of income recognition. A business that ships goods in November but doesn't receive payment until February may find its annual income compressed into a different tax year if the customer delays orders due to tariff uncertainty. For Canadian-Controlled Private Corporations, this can push passive income above the $50,000 threshold that triggers a reduction in the Small Business Deduction, raising the effective tax rate on the first $500,000 of active business income from 9 percent to the general corporate rate. That shift isn't catastrophic, but it's a 16-percentage-point swing that arrives without warning if trade disruptions bunch revenue into a narrow window.
Portfolio Concentration as Mortgage Risk
An investor in Burnaby holds 40 percent of net worth in a single TSX-listed forestry company. The position has performed well. Eighty percent of the company's revenue comes from U.S. sales. In 2024, that concentration didn't matter for mortgage qualification because the investor's employment income was sufficient. In 2026, the same investor applies to refinance. The forestry stock has dropped 22 percent since the U.S. imposed new duties. The lender now sees the asset-to-debt ratio compress, and because the position is concentrated in a sector directly exposed to U.S. trade policy, the underwriter asks for a larger down payment or higher interest rate to offset perceived risk.
Stock portfolios aren't income, but they are collateral. When a significant portion of your assets sits in companies whose revenue depends on U.S. market access, trade policy becomes a variable in your debt capacity. The correct response isn't to panic-sell. It's to model what happens if that position loses another 15 percent and whether your mortgage structure can withstand it.
What to Stress-Test Right Now
Run your debt-service ratios at a 15 percent income reduction and a 10 percent currency move in either direction. If you're self-employed with U.S. clients, assume a lender will discount your income by at least 10 percent before applying the stress test. If you hold equity in a business with concentrated U.S. exposure, calculate the threshold at which a revenue drop forces you to inject personal capital to meet debt covenants. If your portfolio is weighted toward companies with cross-border revenue, identify where you would harvest tax losses if those positions fall sharply and whether those losses offset other gains in the current year.
Trade wars don't announce themselves with forecasts. They arrive as policy, and policy moves faster than refinancing.

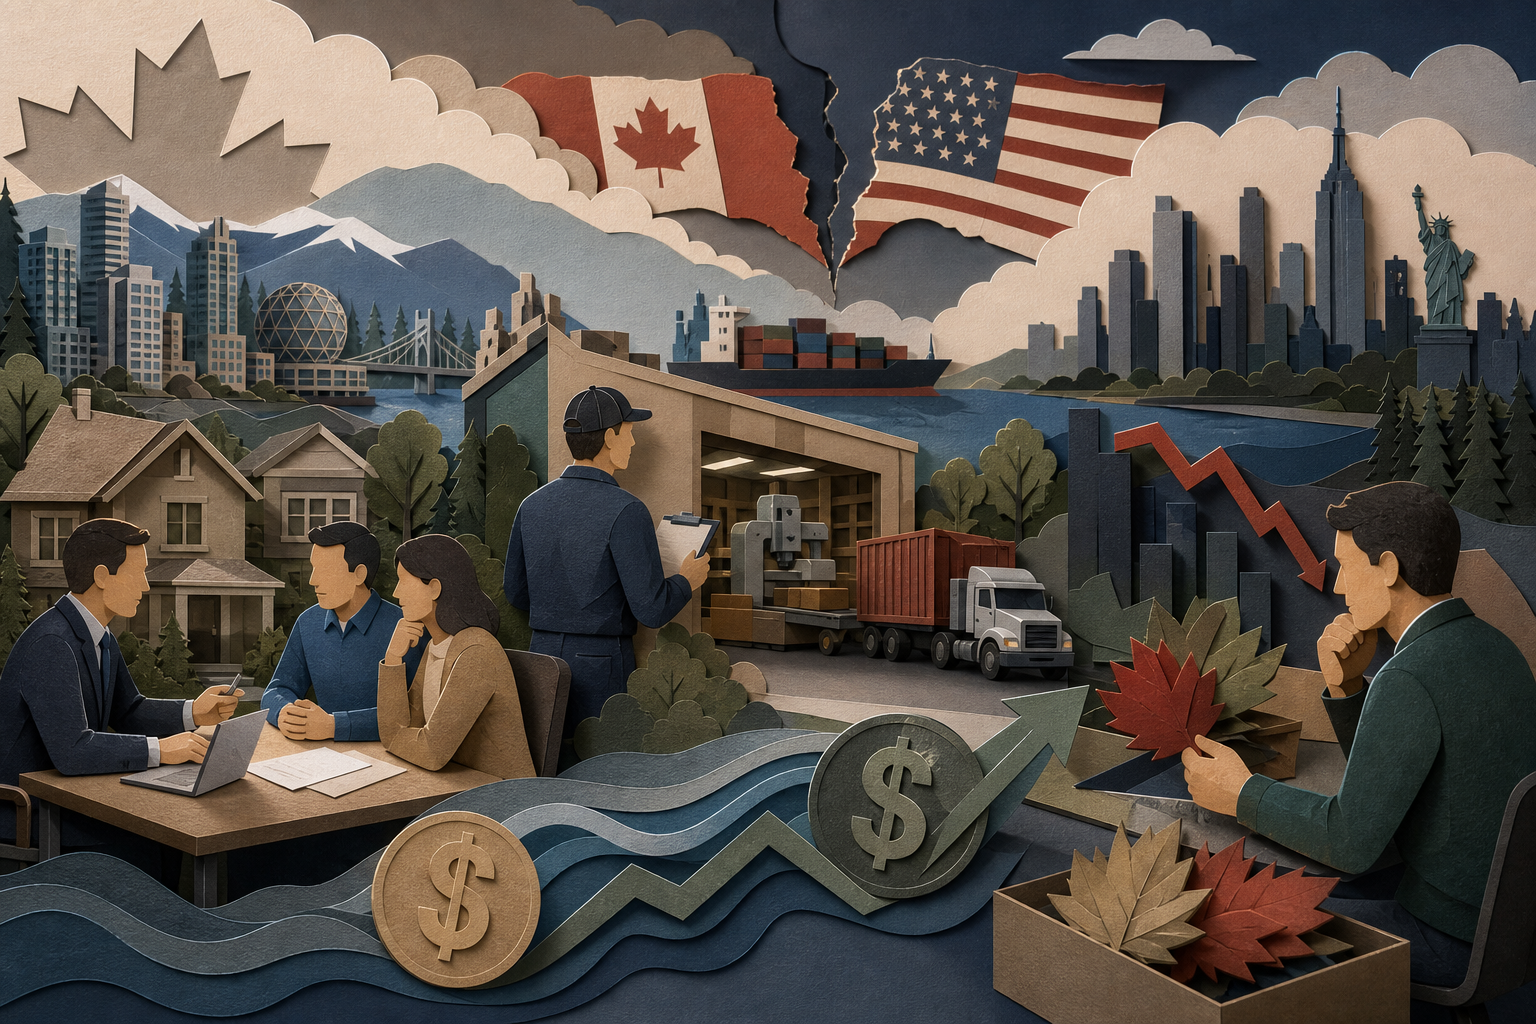
A software consultant in Vancouver invoices three U.S. clients who pay in USD. A manufacturer in Surrey ships 70 percent of output to Washington and Oregon. An investor in Burnaby holds a concentrated position in a TSX-listed company whose revenue is 80 percent American. All three passed mortgage stress tests in 2024. All three may fail the same test in 2026 if a tariff cycle cuts revenue by 15 percent or the Canadian dollar moves sharply in either direction.
Trade friction between Canada and the U.S. used to be something you read about in the business section and forgot by lunch. That assumption no longer holds. Tariff announcements, retaliatory measures, and currency swings now arrive with enough frequency and force to show up in cash flow statements, debt servicing ratios, and tax liabilities within a single fiscal year. For Canadians whose income or assets depend on cross-border trade flows, ignoring U.S. policy risk is no longer a defensible planning posture.
You don't need to predict whether tar Lenders see revenue concentration the moment they open your Notice of Assessment. When 60 percent or more of a business's income comes from U.S. sources, many underwriters treat that as elevated risk, regardless of gross margin. This matters in 2026 because the mortgage stress test already requires borrowers to qualify at the contract rate plus 200 basis points or 5.25 percent, whichever is higher. A business owner who clears that threshold under stable conditions may not clear it once the underwriter applies a discretionary haircut to projected income.
The haircut isn't written into OSFI guidelines. It appears in internal credit policy at individual lenders. A borrower whose T1 shows $180,000 in net business income might see that figure discounted to $153,000 if the underwriter decides cross-border exposure warrants a 15 percent reduction. For self-employed applicants, CMHC already applies a 15 percent gross-up to account for unreimbursed business expenses, but that adjustment moves in the borrower's favor. The trade-exposure discount moves against it, and the two do not offset. A borrower caught in both adjustments can lose 30 percent of stated income before the stress test even begins.
Why Currency Volatility Compounds the Problem
A weaker Canadian dollar should, in theory, help exporters. Revenue earned in USD converts to more CAD when the exchange rate moves from 1.35 to 1.42. But mortgage capacity depends on predictable income, and predictability breaks when the currency swings 5 percent in eight weeks. Lenders model income based on trailing twelve-month averages. A consultant who invoiced US$15,000 per month in 2024 and banked CAD$20,250 at an average rate of 1.35 will see September 2026 deposits of CAD$21,300 if the rate has moved to 1.42. That looks like growth. It isn't. The USD revenue stayed flat while the currency moved.
The reverse scenario is worse. If the CAD strengthens to 1.28 because trade tensions ease or commodity prices fall, the same US$15,000 converts to CAD$19,200. That consultant's stated income just dropped 5 percent without losing a single client. The mortgage underwriter sees declining revenue and may ask for additional reserves or a co-signer. Refinancing at renewal becomes harder. Switching lenders to chase a better rate may not be possible if the new lender recalculates income based on the most recent 24 months of financials, which now show a downward trend.
The Tax Treaty Doesn't Protect You from Operational Disruption
The Canada-U.S. Tax Treaty ensures you won't be taxed twice on the same income. It does not prevent a tariff from shrinking that income in the first place. A Surrey-based manufacturer who ships aluminum components to Oregon faced a 10 percent Section 232 tariff in 2018 and paid it by accepting thinner margins. When the U.S. Department of Commerce increased the all-others rate on Canadian softwood lumber to nearly double the prior level in 2024, British Columbia producers had three options: eat the cost, raise prices and lose orders, or exit certain product lines. None of those paths preserve the income level your tax return showed last year.
Tariffs also disrupt the timing of income recognition. A business that ships goods in November but doesn't receive payment until February may find its annual income compressed into a different tax year if the customer delays orders due to tariff uncertainty. For Canadian-Controlled Private Corporations, this can push passive income above the $50,000 threshold that triggers a reduction in the Small Business Deduction, raising the effective tax rate on the first $500,000 of active business income from 9 percent to the general corporate rate. That shift isn't catastrophic, but it's a 16-percentage-point swing that arrives without warning if trade disruptions bunch revenue into a narrow window.
Portfolio Concentration as Mortgage Risk
An investor in Burnaby holds 40 percent of net worth in a single TSX-listed forestry company. The position has performed well. Eighty percent of the company's revenue comes from U.S. sales. In 2024, that concentration didn't matter for mortgage qualification because the investor's employment income was sufficient. In 2026, the same investor applies to refinance. The forestry stock has dropped 22 percent since the U.S. imposed new duties. The lender now sees the asset-to-debt ratio compress, and because the position is concentrated in a sector directly exposed to U.S. trade policy, the underwriter asks for a larger down payment or higher interest rate to offset perceived risk.
Stock portfolios aren't income, but they are collateral. When a significant portion of your assets sits in companies whose revenue depends on U.S. market access, trade policy becomes a variable in your debt capacity. The correct response isn't to panic-sell. It's to model what happens if that position loses another 15 percent and whether your mortgage structure can withstand it.
What to Stress-Test Right Now
Run your debt-service ratios at a 15 percent income reduction and a 10 percent currency move in either direction. If you're self-employed with U.S. clients, assume a lender will discount your income by at least 10 percent before applying the stress test. If you hold equity in a business with concentrated U.S. exposure, calculate the threshold at which a revenue drop forces you to inject personal capital to meet debt covenants. If your portfolio is weighted toward companies with cross-border revenue, identify where you would harvest tax losses if those positions fall sharply and whether those losses offset other gains in the current year.
Trade wars don't announce themselves with forecasts. They arrive as policy, and policy moves faster than refinancing.
Read Next
Housing Targets Mean Little Without the Trades Workers to Build Them
200 Basis Points or 2%: What OSFI's Qualifying Rate Update Means for You
Canada's U.S. Export Dependency Dropped 3.7 Points Since Your Last Tariff Risk Check
Capital Power's Tariff Shield Holds, But Rate Assumptions Have Shifted: A Portfolio Reality Check for 2026