Fifteen-plus years of BC mortgage experience, distilled into practical writing on buying, renewing, refinancing, and building wealth through real estate.
Capital Power's Tariff Shield Holds, But Rate Assumptions Have Shifted: A Portfolio Reality Check for 2026
The Bank of Canada's policy rate sat at 2.25% on September 2, 2026. That number matters because an entire class of investment advice written six months earlier assumed the floor was still 2.25%, and portfolios built on that assumption now face a different risk distribution than their owners think they do.
Capital Power, the utility stock that held up while tariff-exposed names dropped, was sold all summer as a defensive hedge in a rising-rate environment. The logic went like this: with the policy rate near zero, Capital Power's regulated earnings and contracted cash flows offered downside protection that commodity exporters facing 50% U.S. tariffs lacked. This framing assumed the rate would stay at 2.25%. At 2.25% the trade-off has moved.
The Rate Floor That Moved
In February 2026, the Bank of Canada held rates at 2.25%, the effective lower bound it had maintained through the tariff escalation. By September 2, 2026, the policy rate had held at 2.25% continuously from October 2025 through September 2026. That's not a marginal adjustment. It's a regime change. Utilities priced for a near-zero rate environment don't reprice slowly when the risk-free alternative jumps nine-fold.
The original thesis treated Capital Power as rate-insensitive because its regulated return on equity was locked and its power purchase agreements were inflation-indexed. Both remain true. What changed is the discount rate investors use to value those future cash flows. At 2.25%, a locked 9% ROE on a regulated asset base carried a wide spread over the alternative. At 2.25%, that spread has narrowed by 2 percentage points, and the utility's valuation premium compresses accordingly.
What the Tariff Shield Actually Covered
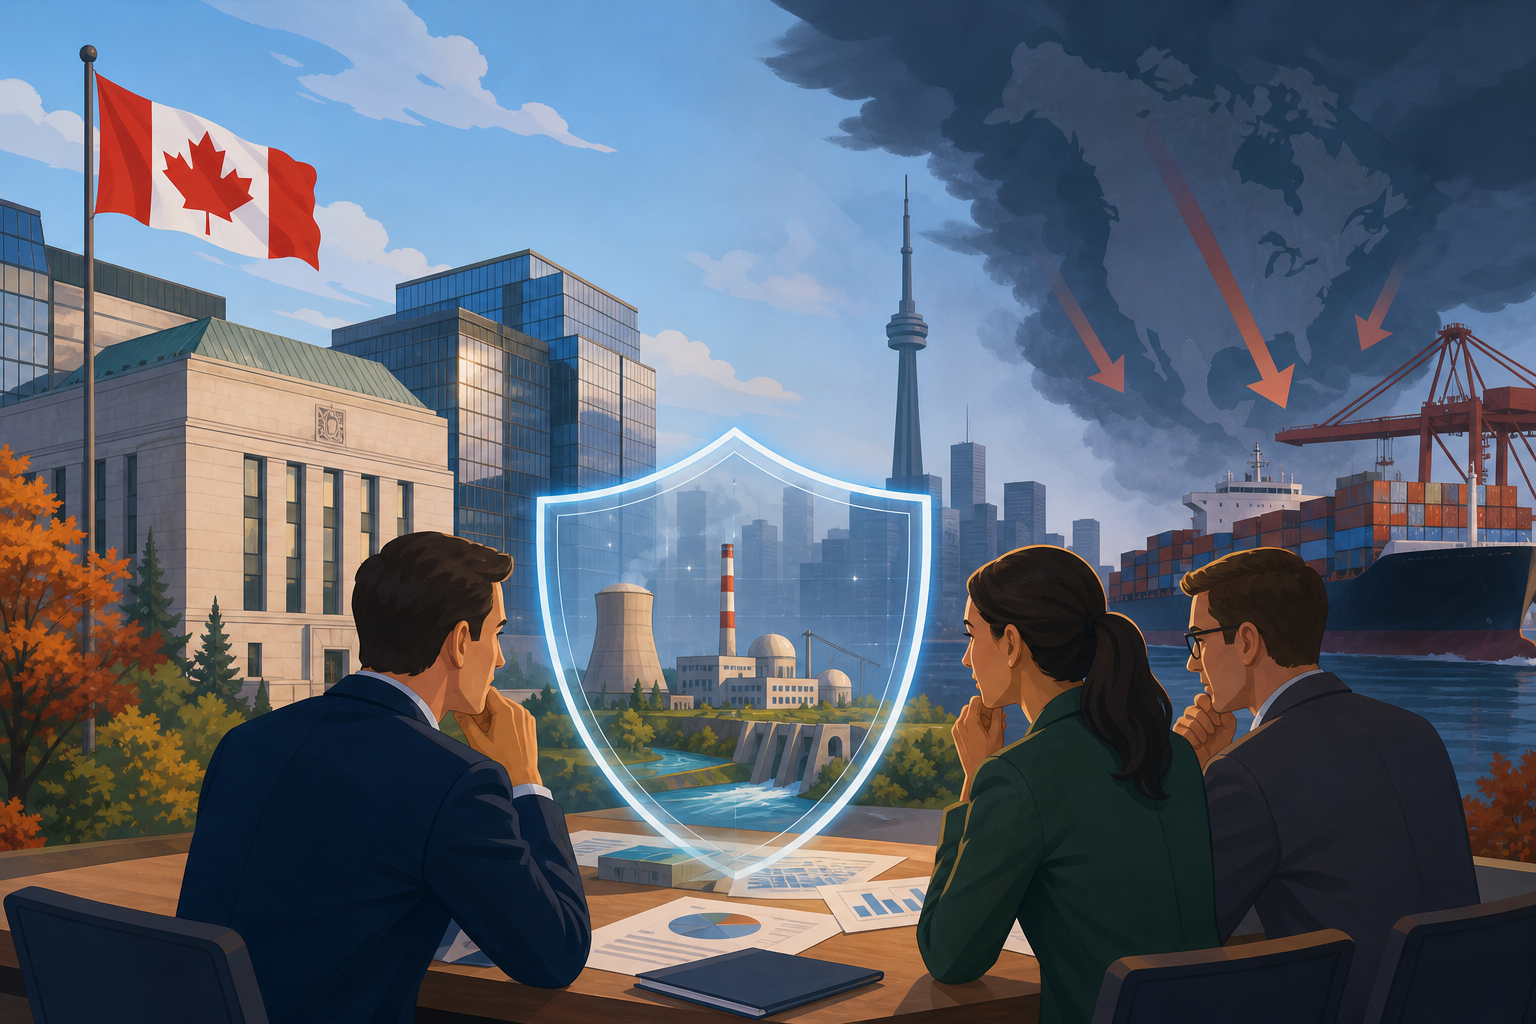
The August 2026 tariff, 50% on $27.6 billion of Canadian goods, effective August 22, hit exporters with direct revenue exposure to U.S. markets. Capital Power's revenue comes almost entirely from electricity sales under long-term contracts across British Columbia and other provinces. No cross-border sales, no tariff impact. That insulation held.
But the tariff shield only protected against one risk. It did nothing for rate risk. In February, investors rotated into Capital Power to escape commodity volatility in an environment where rates were expected to stay near zero. The stock climbed because it was genuinely less exposed to the immediate tariff hit. It's now less attractive than it was in February because the policy rate has remained at 2.25% since October 2025, compressing the spread that made the utility attractive.
The Repositioning That Didn't Happen
Most portfolios that added Capital Power between February and May have not revisited the allocation because the position was sized as a multi-year defensive hold meant to stay in place when the policy rate was 2.25%. The rate is now 2.25%, and the portfolio that made sense at the lower rate is over-allocated to a narrower spread.
The adjustment isn't complicated. If the utility position was sized to provide ballast against tariff-driven volatility in a near-zero rate world, it should now be smaller, and the capital should shift toward either shorter-duration fixed income, now yielding a real return, or tariff-insulated equities with higher nominal growth. The CUSMA review date of July 1, 2026 has passed without resolution, which extends tariff uncertainty, but that uncertainty no longer justifies the same utility weighting it did when cash paid nothing.
What Changed and What To Do
The 2.25% rate that was expected is what we have. The current policy rate is 2.25% as of September 2, 2026. Capital Power remains tariff-insulated, but it is no longer rate-insulated, and anyone holding it as a pure defensive anchor is now holding a rate-sensitive asset in a rising-rate environment. The correct move is to re-run the original allocation logic using 2.25% as the baseline and size the position accordingly. For most portfolios, that means a smaller utility weighting and a reallocation toward assets that can grow earnings faster than the discount rate is rising.
The tariff shield still works. The rate floor it was built on does not exist anymore.

The Bank of Canada's policy rate sat at 2.25% on September 2, 2026. That number matters because an entire class of investment advice written six months earlier assumed the floor was still 2.25%, and portfolios built on that assumption now face a different risk distribution than their owners think they do.
Capital Power, the utility stock that held up while tariff-exposed names dropped, was sold all summer as a defensive hedge in a rising-rate environment. The logic went like this: with the policy rate near zero, Capital Power's regulated earnings and contracted cash flows offered downside protection that commodity exporters facing 50% U.S. tariffs lacked. This framing assumed the rate would stay at 2.25%. At 2.25% the trade-off has moved.
The Rate Floor That Moved
In February 2026, the Bank of Canada held rates at 2.25%, the effective lower bound it had maintained through the tariff escalation. By September 2, 2026, the policy rate had held at 2.25% continuously from October 2025 through September 2026. That's not a marginal adjustment. It's a regime change. Utilities priced for a near-zero rate environment don't reprice slowly when the risk-free alternative jumps nine-fold.
The original thesis treated Capital Power as rate-insensitive because its regulated return on equity was locked and its power purchase agreements were inflation-indexed. Both remain true. What changed is the discount rate investors use to value those future cash flows. At 2.25%, a locked 9% ROE on a regulated asset base carried a wide spread over the alternative. At 2.25%, that spread has narrowed by 2 percentage points, and the utility's valuation premium compresses accordingly.
What the Tariff Shield Actually Covered
The August 2026 tariff, 50% on $27.6 billion of Canadian goods, effective August 22, hit exporters with direct revenue exposure to U.S. markets. Capital Power's revenue comes almost entirely from electricity sales under long-term contracts across British Columbia and other provinces. No cross-border sales, no tariff impact. That insulation held.
But the tariff shield only protected against one risk. It did nothing for rate risk. In February, investors rotated into Capital Power to escape commodity volatility in an environment where rates were expected to stay near zero. The stock climbed because it was genuinely less exposed to the immediate tariff hit. It's now less attractive than it was in February because the policy rate has remained at 2.25% since October 2025, compressing the spread that made the utility attractive.
The Repositioning That Didn't Happen
Most portfolios that added Capital Power between February and May have not revisited the allocation because the position was sized as a multi-year defensive hold meant to stay in place when the policy rate was 2.25%. The rate is now 2.25%, and the portfolio that made sense at the lower rate is over-allocated to a narrower spread.
The adjustment isn't complicated. If the utility position was sized to provide ballast against tariff-driven volatility in a near-zero rate world, it should now be smaller, and the capital should shift toward either shorter-duration fixed income, now yielding a real return, or tariff-insulated equities with higher nominal growth. The CUSMA review date of July 1, 2026 has passed without resolution, which extends tariff uncertainty, but that uncertainty no longer justifies the same utility weighting it did when cash paid nothing.
What Changed and What To Do
The 2.25% rate that was expected is what we have. The current policy rate is 2.25% as of September 2, 2026. Capital Power remains tariff-insulated, but it is no longer rate-insulated, and anyone holding it as a pure defensive anchor is now holding a rate-sensitive asset in a rising-rate environment. The correct move is to re-run the original allocation logic using 2.25% as the baseline and size the position accordingly. For most portfolios, that means a smaller utility weighting and a reallocation toward assets that can grow earnings faster than the discount rate is rising.
The tariff shield still works. The rate floor it was built on does not exist anymore.
Sources
Read Next
Housing Targets Mean Little Without the Trades Workers to Build Them
200 Basis Points or 2%: What OSFI's Qualifying Rate Update Means for You
Canada's U.S. Export Dependency Dropped 3.7 Points Since Your Last Tariff Risk Check
Small Business Deduction Passive Income Threshold Drops to $50,000 in Most Provinces: What Cross-Border Earners Need to Recalculate Now