Fifteen-plus years of BC mortgage experience, distilled into practical writing on buying, renewing, refinancing, and building wealth through real estate.
Canada's U.S. Export Dependency Dropped 3.7 Points Since Your Last Tariff Risk Check
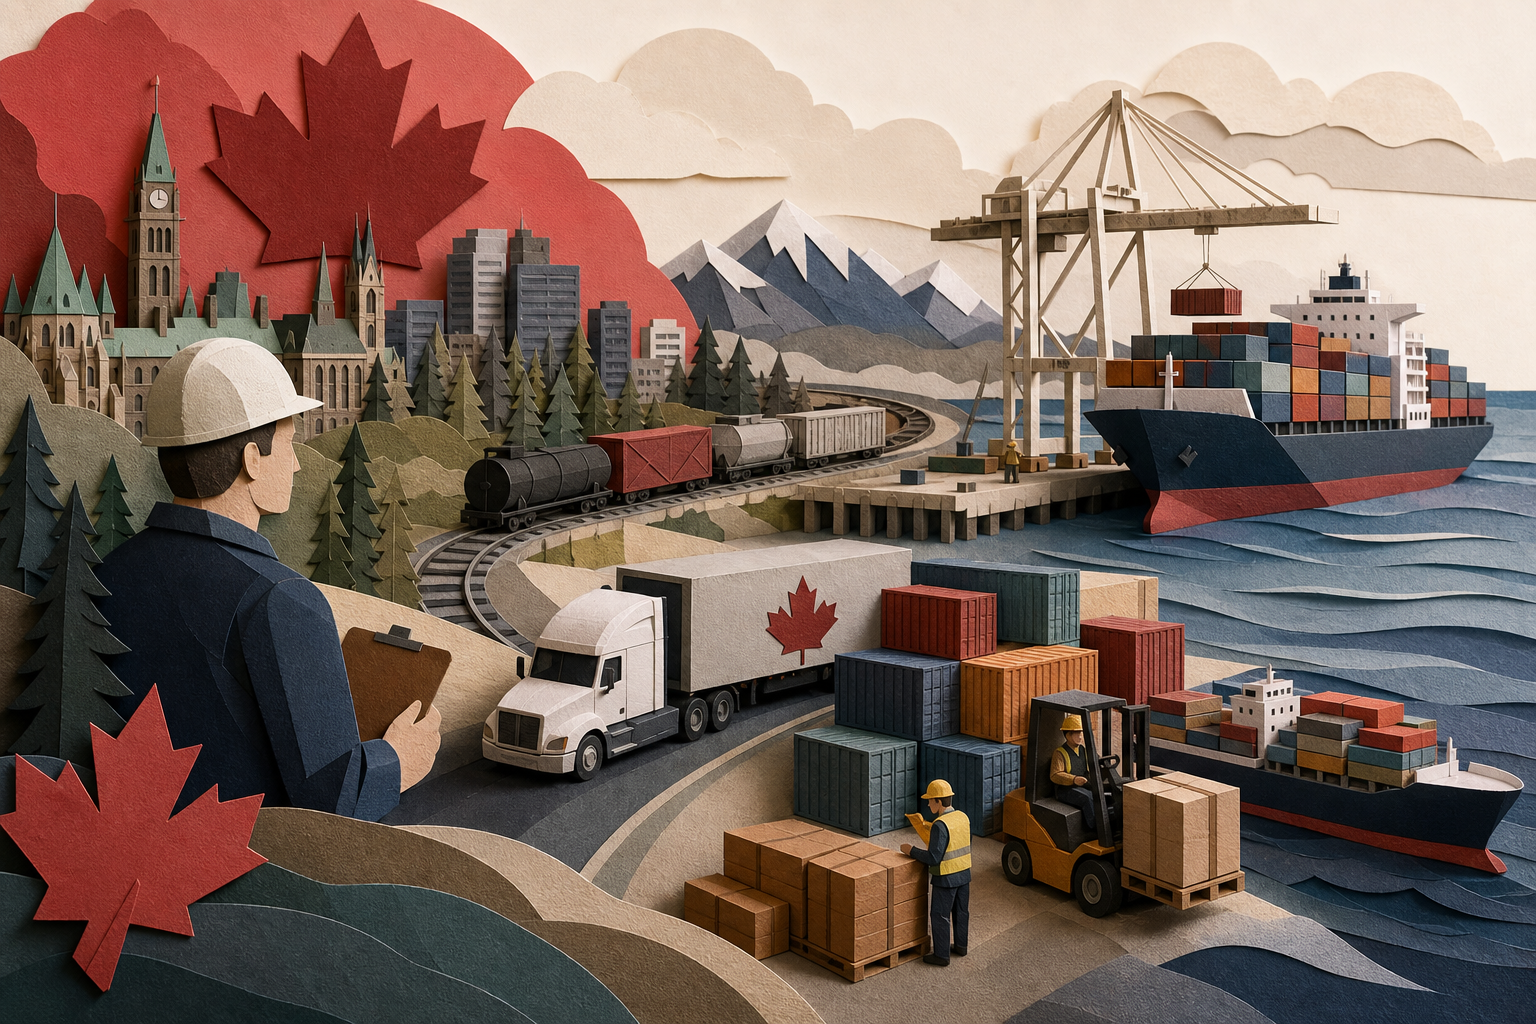
Seventy-one point seven percent of Canada's merchandise exports went to the U.S. at the start of 2025. As of August 2026, the number is 68%.
That's not a rounding difference. It's a 3.7-point drop in export concentration over roughly twenty months. The kind of shift that doesn't happen by accident and doesn't reverse quickly.
If you sized up tariff exposure using the old figure, and most of the coverage still floating around the internet did, you overestimated how much of Canada's export revenue sits in one basket. Not by a little. By nearly four percentage points of total merchandise exports, which in dollar terms is tens of billions in annual trade that now flows somewhere other than south.
The rebalancing you didn't notice
The 71.7% figure came from Statistics Canada's January 2025 trade data. It showed up in federal briefings, provincial risk assessments, and every second tariff-risk explainer published that year. It became the shorthand number.
Visual Capitalist published updated figures in August 2026 showing the U.S. share at 68%. That's sourced from the same federal trade data, just twenty months later. The drop didn't come from a one-month anomaly. It came from sustained reallocation across multiple quarters while half the commentary was still citing last year's number.
Three-point-seven percentage points of export dependency doesn't vanish because Canadian exporters got nervous and filed some new customs forms. It vanishes because new contracts were signed with buyers in other markets, shipping routes were re-negotiated, and enough firms decided the U.S. customer concentration was a structural problem worth paying to fix.
What moved and where it went
The August 2026 data doesn't break out sector-by-sector reallocation in the summary tables, but the aggregate tells you this wasn't just oil and gas finding Asian buyers. Merchandise exports include everything from forestry products to manufactured goods to agriculture. A four-point shift across that base means multiple industries found enough demand outside the U.S. to justify the higher logistics cost and longer payment cycles that come with serving Europe, Asia, or Latin America.
Some of that migration was defensive. When the U.S. imposed 50% tariffs on $27.6 billion of Canadian goods in August 2026, the firms hit hardest were the ones that hadn't diversified. The ones that had spent 2025 and early 2026 building non-U.S. channels had somewhere to send the volume when the tariff landed.
But most of it wasn't tariff panic. It was arithmetic. Sixty-eight percent is still a dangerous concentration. The difference is that 68% is a number moving in the right direction, and 71.7% was a number sitting still while the risk got louder.
What you should check now
If you modelled tariff exposure, currency swings, or cross-border revenue risk using 71.7%, the model is wrong. Not slightly off. Structurally wrong, because it assumes a trade dependence that no longer matches the actual flow of goods.
Run it again at 68% and see what changes. For a business with significant export revenue, a 3.7-point difference in U.S. exposure can flip a borderline expansion decision or change the hurdle rate on a new U.S. customer contract.
If you're a lender sizing trade finance or underwriting cross-border receivables, the risk distribution shifted. A portfolio that looked 72% U.S.-dependent eighteen months ago is measurably more diversified now, assuming your borrowers moved with the national trend. If they didn't, they're more concentrated than the aggregate, and that's its own signal.
For policymakers still working from the 71.7% anchor, the August number says the export base responded faster than the briefing notes did. The dependency is still real. It's just no longer what it was when the last round of risk assessments went out.
The 68% figure comes from Visual Capitalist's August 26, 2026 analysis of Canadian export data. It replaces the 71.7% figure published by Statistics Canada for January 2025. The gap between them is not a data revision. It's twenty months of exporters doing exactly what everyone said they should do, while most of the coverage kept citing the old number.

Seventy-one point seven percent of Canada's merchandise exports went to the U.S. at the start of 2025. As of August 2026, the number is 68%.
That's not a rounding difference. It's a 3.7-point drop in export concentration over roughly twenty months. The kind of shift that doesn't happen by accident and doesn't reverse quickly.
If you sized up tariff exposure using the old figure, and most of the coverage still floating around the internet did, you overestimated how much of Canada's export revenue sits in one basket. Not by a little. By nearly four percentage points of total merchandise exports, which in dollar terms is tens of billions in annual trade that now flows somewhere other than south.
The rebalancing you didn't notice
The 71.7% figure came from Statistics Canada's January 2025 trade data. It showed up in federal briefings, provincial risk assessments, and every second tariff-risk explainer published that year. It became the shorthand number.
Visual Capitalist published updated figures in August 2026 showing the U.S. share at 68%. That's sourced from the same federal trade data, just twenty months later. The drop didn't come from a one-month anomaly. It came from sustained reallocation across multiple quarters while half the commentary was still citing last year's number.
Three-point-seven percentage points of export dependency doesn't vanish because Canadian exporters got nervous and filed some new customs forms. It vanishes because new contracts were signed with buyers in other markets, shipping routes were re-negotiated, and enough firms decided the U.S. customer concentration was a structural problem worth paying to fix.
What moved and where it went
The August 2026 data doesn't break out sector-by-sector reallocation in the summary tables, but the aggregate tells you this wasn't just oil and gas finding Asian buyers. Merchandise exports include everything from forestry products to manufactured goods to agriculture. A four-point shift across that base means multiple industries found enough demand outside the U.S. to justify the higher logistics cost and longer payment cycles that come with serving Europe, Asia, or Latin America.
Some of that migration was defensive. When the U.S. imposed 50% tariffs on $27.6 billion of Canadian goods in August 2026, the firms hit hardest were the ones that hadn't diversified. The ones that had spent 2025 and early 2026 building non-U.S. channels had somewhere to send the volume when the tariff landed.
But most of it wasn't tariff panic. It was arithmetic. Sixty-eight percent is still a dangerous concentration. The difference is that 68% is a number moving in the right direction, and 71.7% was a number sitting still while the risk got louder.
What you should check now
If you modelled tariff exposure, currency swings, or cross-border revenue risk using 71.7%, the model is wrong. Not slightly off. Structurally wrong, because it assumes a trade dependence that no longer matches the actual flow of goods.
Run it again at 68% and see what changes. For a business with significant export revenue, a 3.7-point difference in U.S. exposure can flip a borderline expansion decision or change the hurdle rate on a new U.S. customer contract.
If you're a lender sizing trade finance or underwriting cross-border receivables, the risk distribution shifted. A portfolio that looked 72% U.S.-dependent eighteen months ago is measurably more diversified now, assuming your borrowers moved with the national trend. If they didn't, they're more concentrated than the aggregate, and that's its own signal.
For policymakers still working from the 71.7% anchor, the August number says the export base responded faster than the briefing notes did. The dependency is still real. It's just no longer what it was when the last round of risk assessments went out.
The 68% figure comes from Visual Capitalist's August 26, 2026 analysis of Canadian export data. It replaces the 71.7% figure published by Statistics Canada for January 2025. The gap between them is not a data revision. It's twenty months of exporters doing exactly what everyone said they should do, while most of the coverage kept citing the old number.
Read Next
Housing Targets Mean Little Without the Trades Workers to Build Them
200 Basis Points or 2%: What OSFI's Qualifying Rate Update Means for You
Capital Power's Tariff Shield Holds, But Rate Assumptions Have Shifted: A Portfolio Reality Check for 2026
Small Business Deduction Passive Income Threshold Drops to $50,000 in Most Provinces: What Cross-Border Earners Need to Recalculate Now