Fifteen-plus years of BC mortgage experience, distilled into practical writing on buying, renewing, refinancing, and building wealth through real estate.
60% of Canadian Mortgages Renew by 2026: What the Numbers Actually Mean for Your Payment
The couple who signed their five-year fixed at 1.64% in March 2021 will see their term end in March 2026. That rate no longer exists. The replacement rate, even after recent Bank of Canada cuts, sits between 4.5% and 5.25% depending on their equity position and whether they shop around. That spread, roughly three percentage points, is the payment shock.
The 60% figure that appears in headlines refers to the share of outstanding Canadian mortgages expected to renew by the end of 2026, per Bank of Canada tracking. That translates to roughly $600 billion in mortgage volume moving from pandemic-era pricing to current market rates through the end of 2026. The cliff metaphor is misleading. A distributed wave of individual household recalculations will happen every month through late 2026, each one quiet until the renewal notice arrives.
The arithmetic of the jump
A $400,000 mortgage at 1.79% with a 25-year amortization carries a monthly payment of roughly $1,660. The same balance renewed at 4.79% pushes the payment to $2,290. That is a $630 increase, or 38%, before any principal reduction from the first term is factored in. Borrowers who paid down $40,000 over five years still face a payment in the $2,100 range. The rate environment matters more than the progress made.
The Bank of Canada's stress test required these borrowers to qualify at roughly 5.25% when they took the loan, so the system assumed they could handle this. The assumption was theoretical. The practice of actually writing a cheque $600 higher every month, indefinitely, is different. Discretionary spending absorbs the first cut. RRSP contributions stop. The car lease doesn't renew. Restaurant visits drop. This is how the "wealth effect" works in reverse at the household level, and in aggregate it shows up as slower GDP growth in regions where mortgage debt is concentrated.
What equity does
Homeowners in British Columbia who bought before 2021 likely have significant equity. A property purchased in 2018 for $450,000 and now worth $650,000 provides a refinancing cushion that a 2021 buyer with 10% down does not have. Equity allows for amortization extensions, it allows for switching lenders without requalifying under the stress test, and it allows for accessing a home equity line of credit to smooth the payment increase over time. That cushion is unequally distributed. First-time buyers from 2020 and 2021 who stretched to qualify are the segment most exposed.
The soft-landing question
Mortgage delinquencies in British Columbia rose to 0.25% in the first quarter of 2026, even as renewal volumes climbed. This is partly because homeowners prioritize the mortgage above every other obligation, and partly because lenders have been willing to extend amortizations quietly rather than force distress sales. The Financial Consumer Agency of Canada issued guidelines in 2023 requiring proactive outreach to at-risk borrowers, and banks have complied. Lenders have extended amortizations beyond 30 years, which means borrowers pay more interest over the life of the loan but avoid payment shock in the near term.
The rate cuts that began mid-2026 have narrowed the gap between 2021 rates and today's offerings, but the gap has not closed. The "new normal" for five-year fixed rates is expected to settle in the mid-4% range rather than below 2%, making the shock smaller than it would have been in 2024, though it has not disappeared.
The renewal pressure is a slope rather than a vertical cliff. Each household hits it on their own schedule, and the system has absorbed most of the impact so far through term extensions and spending cuts rather than defaults. Whether that holds depends less on the rate environment than on the labour market. As long as British Columbia's unemployment rate stays low, most borrowers will keep paying. The question is what they stop paying for instead.

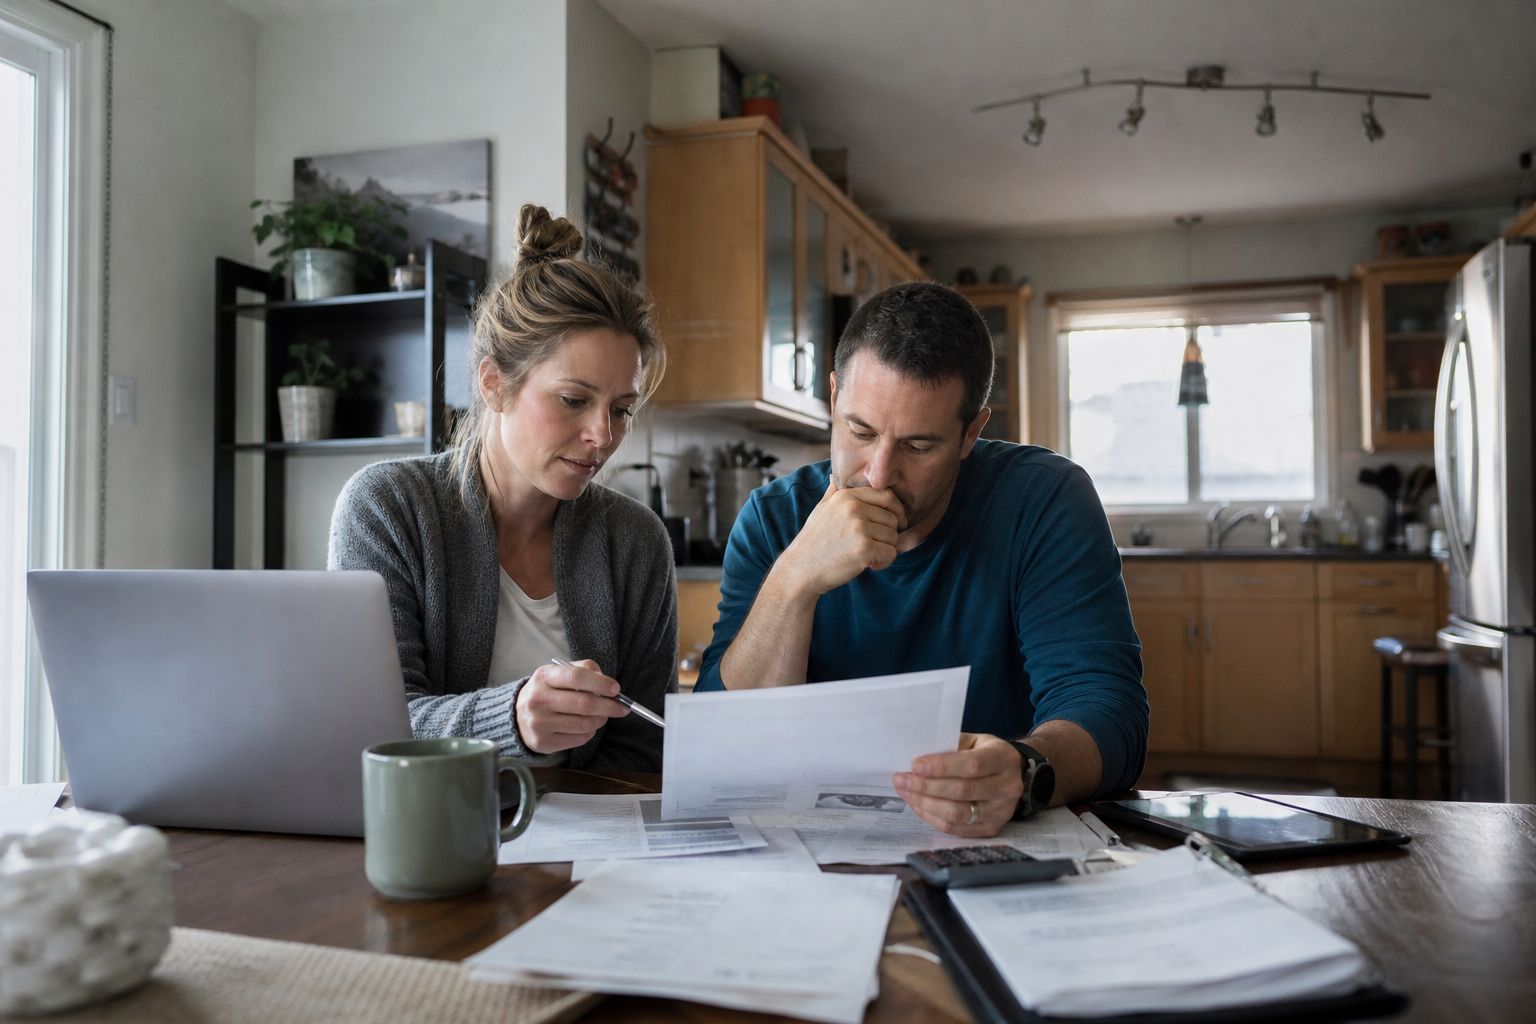
The couple who signed their five-year fixed at 1.64% in March 2021 will see their term end in March 2026. That rate no longer exists. The replacement rate, even after recent Bank of Canada cuts, sits between 4.5% and 5.25% depending on their equity position and whether they shop around. That spread, roughly three percentage points, is the payment shock.
The 60% figure that appears in headlines refers to the share of outstanding Canadian mortgages expected to renew by the end of 2026, per Bank of Canada tracking. That translates to roughly $600 billion in mortgage volume moving from pandemic-era pricing to current market rates through the end of 2026. The cliff metaphor is misleading. A distributed wave of individual household recalculations will happen every month through late 2026, each one quiet until the renewal notice arrives.
The arithmetic of the jump
A $400,000 mortgage at 1.79% with a 25-year amortization carries a monthly payment of roughly $1,660. The same balance renewed at 4.79% pushes the payment to $2,290. That is a $630 increase, or 38%, before any principal reduction from the first term is factored in. Borrowers who paid down $40,000 over five years still face a payment in the $2,100 range. The rate environment matters more than the progress made.
The Bank of Canada's stress test required these borrowers to qualify at roughly 5.25% when they took the loan, so the system assumed they could handle this. The assumption was theoretical. The practice of actually writing a cheque $600 higher every month, indefinitely, is different. Discretionary spending absorbs the first cut. RRSP contributions stop. The car lease doesn't renew. Restaurant visits drop. This is how the "wealth effect" works in reverse at the household level, and in aggregate it shows up as slower GDP growth in regions where mortgage debt is concentrated.
What equity does
Homeowners in British Columbia who bought before 2021 likely have significant equity. A property purchased in 2018 for $450,000 and now worth $650,000 provides a refinancing cushion that a 2021 buyer with 10% down does not have. Equity allows for amortization extensions, it allows for switching lenders without requalifying under the stress test, and it allows for accessing a home equity line of credit to smooth the payment increase over time. That cushion is unequally distributed. First-time buyers from 2020 and 2021 who stretched to qualify are the segment most exposed.
The soft-landing question
Mortgage delinquencies in British Columbia rose to 0.25% in the first quarter of 2026, even as renewal volumes climbed. This is partly because homeowners prioritize the mortgage above every other obligation, and partly because lenders have been willing to extend amortizations quietly rather than force distress sales. The Financial Consumer Agency of Canada issued guidelines in 2023 requiring proactive outreach to at-risk borrowers, and banks have complied. Lenders have extended amortizations beyond 30 years, which means borrowers pay more interest over the life of the loan but avoid payment shock in the near term.
The rate cuts that began mid-2026 have narrowed the gap between 2021 rates and today's offerings, but the gap has not closed. The "new normal" for five-year fixed rates is expected to settle in the mid-4% range rather than below 2%, making the shock smaller than it would have been in 2024, though it has not disappeared.
The renewal pressure is a slope rather than a vertical cliff. Each household hits it on their own schedule, and the system has absorbed most of the impact so far through term extensions and spending cuts rather than defaults. Whether that holds depends less on the rate environment than on the labour market. As long as British Columbia's unemployment rate stays low, most borrowers will keep paying. The question is what they stop paying for instead.
Sources
Read Next
Housing Targets Mean Little Without the Trades Workers to Build Them
200 Basis Points or 2%: What OSFI's Qualifying Rate Update Means for You
Canada's U.S. Export Dependency Dropped 3.7 Points Since Your Last Tariff Risk Check
Capital Power's Tariff Shield Holds, But Rate Assumptions Have Shifted: A Portfolio Reality Check for 2026